


Air Fryer Market Saturation: Where the Next B2B Growth Opportunity Actually Lies
Key Facts
- The European air fryer market was valued at USD 394.59 million in 2025, growing at a moderate CAGR of 7.9% through 2034 — a sharp deceleration from the 20%+ annual growth rates seen between 2020 and 2022. (Source: Market Data Forecast, April 2026)
- The Europe household coffee machine market is worth USD 5.55 billion in 2026, growing at 5.31% CAGR to reach USD 7.19 billion by 2031 — a category nearly 14× the size of air fryers that most China-based OEM factories have underserved. (Source: Mordor Intelligence, June 2026)
- Europe's overall small kitchen appliances market reached USD 9.06 billion in 2025, projected to hit USD 13.12 billion by 2033 (CAGR 4.7%) — with growth increasingly concentrated in smart, multi-function, and health-adjacent categories rather than single-purpose fryers. (Source: Grand View Research, 2026)
- The Europe Smart Kitchen Appliances market is projected to reach USD 14.17 billion by 2030, growing at 16.3% CAGR — the fastest-expanding segment in the entire kitchen appliance universe, outpacing air fryers by a factor of more than 2×. (Source: Grand View Research, January 2026)
- The global multi-functional air fryer market alone is estimated at USD 3.17 billion in 2026, growing to USD 8.87 billion by 2035 — signalling that even within the air fryer space, buyers are pivoting from single-function to multi-function SKUs, compressing margins on basic models. (Source: Business Research Insights, 2026)
The Air Fryer Boom Is Real — But It Is Also Maturing
Let's be precise: the air fryer market is not collapsing. It is maturing. There is a critical difference, and misreading it is costing some B2B buyers real money.
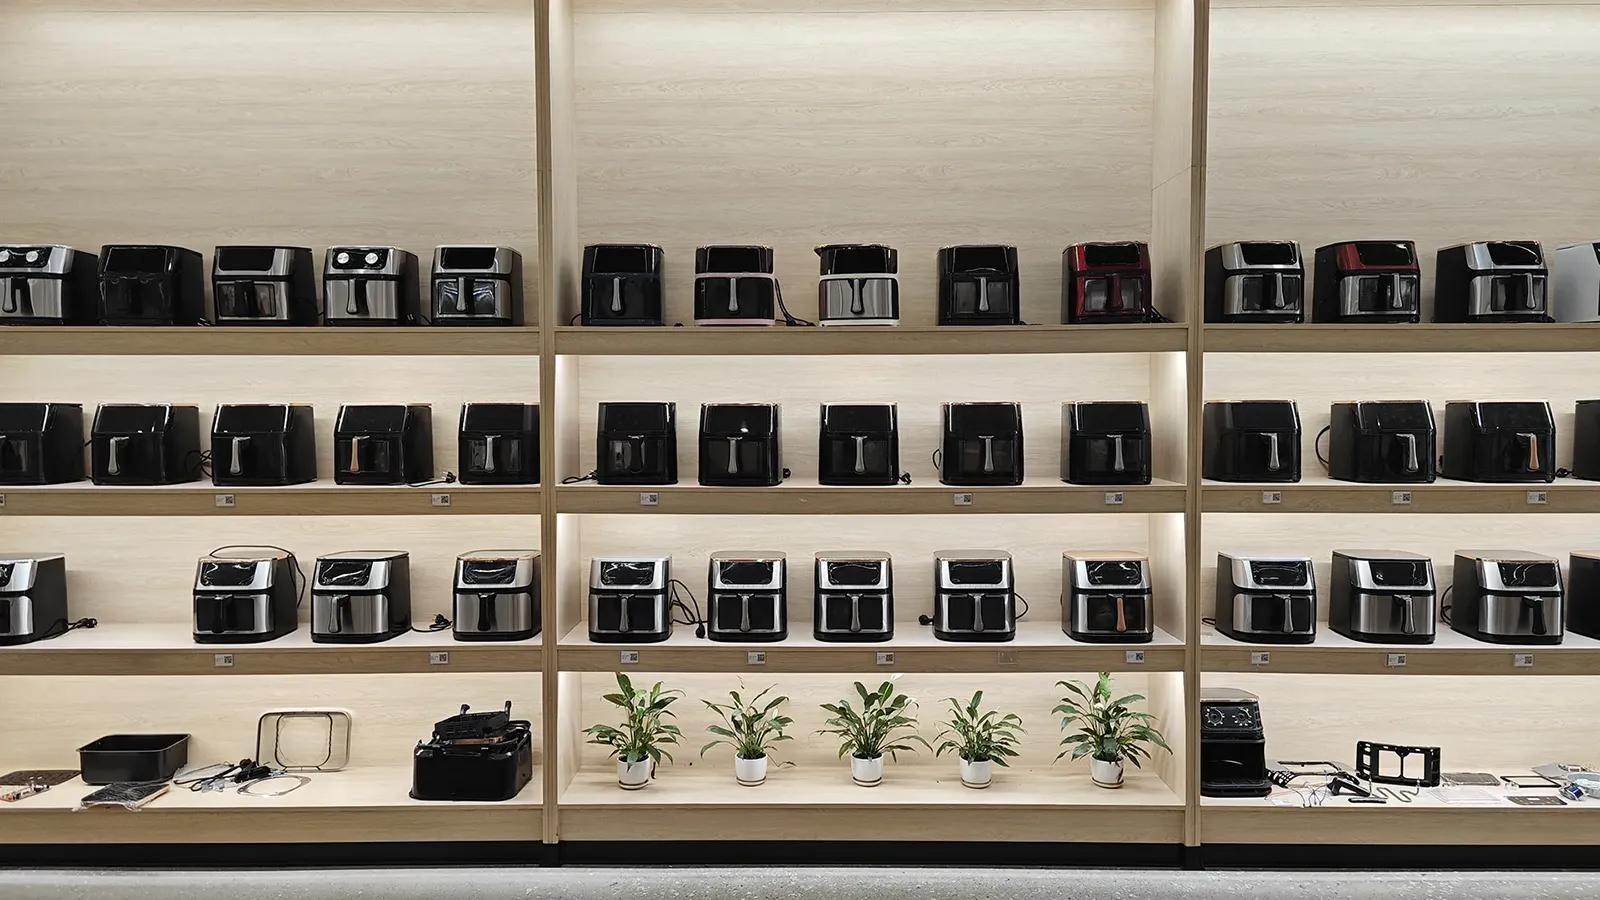
At USD 394.59 million in Europe in 2025, growing at 7.9% annually, air fryers remain a healthy category. But healthy is not the same as exceptional. Between 2020 and 2022, early European importers of dual-basket air fryers and air fryer ovens were riding a wave of novelty-driven demand. That wave has crested. Today, the category faces three structural pressures:
- Household penetration saturation in core markets (UK, Germany, France) — in some demographics, 40%+ of households already own one
- Price compression from the proliferation of Chinese-sourced white-label models, squeezing margins for importers without differentiated positioning
- Shelf-space competition as European retailers consolidate SKUs and demand GS-certified, CE-compliant products with clear differentiation — see the GS certification deep dive for what that now entails
This is not a reason to exit air fryers. It is a reason to stop treating them as your entire catalogue.
From APEXDURA's sourcing desk: We have seen a consistent pattern in the past 18 months — buyers who expanded from single air fryer SKUs into adjacent categories (coffee machines, blenders, multi-cookers) are now placing 40–60% of their reorder volume in those new categories, while maintaining air fryer as a baseline. The buyers who doubled down on air fryer only are now negotiating harder on price because that's the only lever they have left.
Three Categories With the Real B2B Upside in 2026

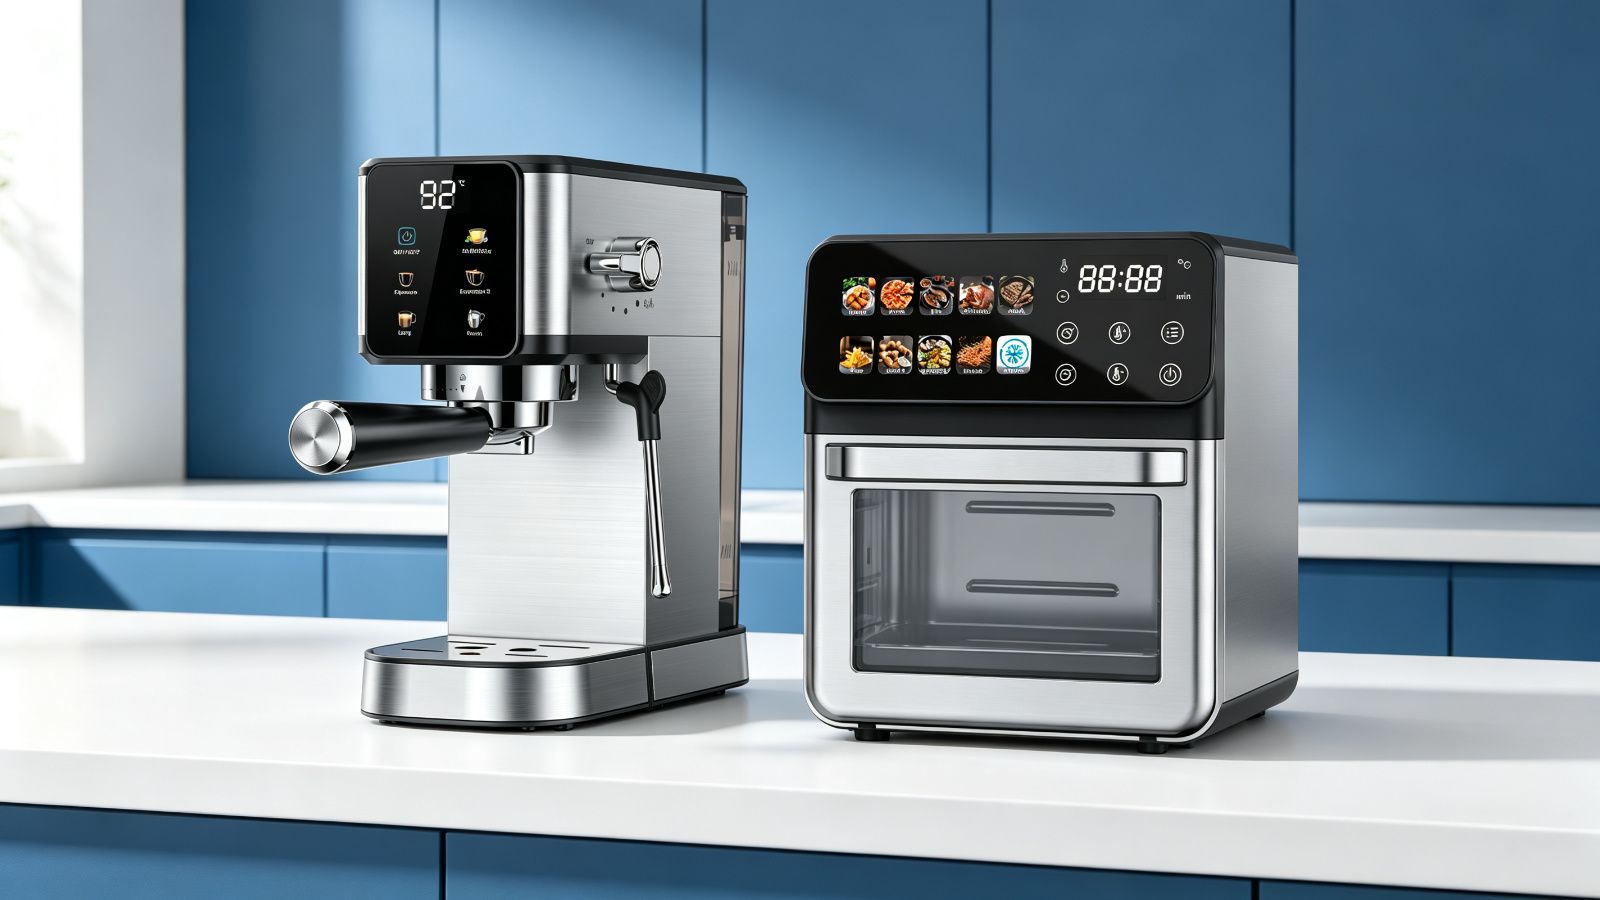
1. Coffee Machines: The Underserved B2B Giant
The European household coffee machine market is worth USD 5.55 billion in 2026 — and the professional/commercial segment adds another USD 2.21 billion on top of that. Yet the B2B content ecosystem, the number of China-based OEM suppliers with serious export documentation, and the average catalogue depth of European importers all dramatically underserve this market relative to air fryers.
For buyers already sourcing from China, the coffee machine category offers something air fryers currently cannot: genuine price stratification with sustainable margins. Entry-level drip coffee makers compete on price; espresso and bean-to-cup machines compete on features, certifications, and brand story. The coffee maker B2B sourcing guide covers the segmentation in detail — but the headline is that premium-tier coffee machines carry 35–60% higher per-unit margins than comparable air fryer SKUs at equivalent quality tiers.
2. Personal Blenders and Commercial Smoothie Stations: Speed-to-Market Advantage
Personal blenders are riding the Europe-wide health-centric kitchen trend documented in the 2026 European consumer trends report. The B2B angle is sharpened by the food-service recovery: cafes, hotel breakfast stations, and corporate wellness programmes are restocking blender fleets at scale, creating MOQ-friendly bulk orders that air fryer buyers rarely see.
The blender B2B sourcing guide details the full commercial vs. personal segment split, but the strategic point is simple: blender is a category where European importers are actively looking for new China-based OEM partners with CE documentation — and finding fewer credible ones than they would like.
3. Smart Multi-Cookers: The Long-Tail Play
At 16.3% CAGR through 2030, smart kitchen appliances are the fastest-growing segment in European kitchen retail. Within that, smart multi-cookers — devices that pressure-cook, slow-cook, sauté, steam, and air-fry in one unit — are cannibalising single-purpose air fryer sales in the mid-to-premium market tier.
The sourcing challenge here is certification complexity: smart multi-cookers require CE, EMC compliance, and increasingly ErP 2026 standby power verification. But that complexity is also a moat — buyers who navigate it with a credible OEM/ODM partner lock out competitors who cannot.
How to Diversify Without Abandoning Air Fryer
The right move is not an abrupt category pivot. It is a deliberate portfolio expansion anchored in your existing logistics, certification, and buyer relationships.

A practical framework for European importers currently over-indexed on air fryers:
Step 1 — Audit your current buyer base. Which of your existing retail or foodservice buyers already stock coffee machines or blenders from other suppliers? That's your fastest cross-sell surface.
Step 2 — Identify the certification bridge. If your current OEM partner already holds CE certification and ISO 9001 for air fryers, ask whether they produce coffee machines or blenders under the same quality system. Factories that do eliminate most of the supplier onboarding risk.
Step 3 — Run a small-batch market test. Order one or two new-category SKUs under OEM terms, consistent with your MOQ negotiation playbook, before committing to a full range. Use the sample management workflow you already have.
The H2 2026 European sourcing signals report and the European mid-year market check both confirm this pattern: buyers diversifying into adjacent categories in early 2026 are reporting stronger Q3 order books than those who stayed air fryer-only.
FAQ
Q1: Is the air fryer market declining in Europe? No — it is maturing. The European air fryer market is still growing at ~7.9% CAGR through 2034, but the explosive 20%+ growth years are over. For B2B importers, this means shifting from volume growth to margin management and differentiation within the category.
Q2: Which European market still has the most untapped air fryer B2B potential? Eastern Europe — particularly Poland, Czech Republic, and Romania — where household penetration rates remain well below Western European levels. The Poland and Eastern Europe guide covers entry strategy in detail.
Q3: What is the single biggest sourcing opportunity beyond air fryers in 2026? Coffee machines. The European household coffee machine market is nearly 14× the size of the air fryer market in Europe, growing steadily, and severely under-supplied by China-based OEM partners with credible CE and GS certification documentation.
Q4: How do I know if my current OEM factory can produce coffee machines or blenders? Request their product capability statement and existing CE certification scope from their factory certification documentation. Factories with broad IEC 60335 coverage (multiple part 2 sub-standards) can typically extend into adjacent categories with limited retooling.
Q5: Should I stop sourcing air fryers entirely? No. Air fryers remain a healthy, proven category with established European buyer demand. The strategic shift is to treat air fryers as the anchor of a diversified kitchen appliance portfolio — not the entire portfolio. Adding one or two adjacent categories reduces buyer concentration risk and opens new revenue streams.
About APEXDURA: Your Full-Range Kitchen Appliance OEM Partner
APEXDURA manufactures and exports the full spectrum of kitchen appliances — air fryers, coffee machines, blenders, electric pressure cookers, microwave ovens, and meat grinders — from a single ISO 9001-certified facility in Zhongshan, China.
✅ One factory, full portfolio — consolidate multi-category sourcing under a single OEM/ODM partner, reducing supplier management overhead ✅ CE + GS pre-validated designs — certification documentation prepared before sample stage, not retrofitted after ✅ 100% pre-shipment inspection — every unit audited before container loading ✅ Flexible MOQ structure — supports category testing with smaller first orders before full range commitment
Ready to expand your European kitchen appliance portfolio beyond air fryers?
📧 Email: devin@zszhenmei.com 📱 WhatsApp: +86 136 1272 5240 🔗 Explore the full range: https://www.apexdura.com/oem-odm/#contact-us?utm_source=news&utm_medium=article&utm_campaign=air-fryer-market-saturation-next-b2b-growth-opportunity-europe-2026