


Aldi, Lidl, and Private Label: How Discount Retail Is Reshaping Kitchen Appliance B2B
Aldi, Lidl, and Private Label: How Discount Retail Is Reshaping Kitchen Appliance B2B
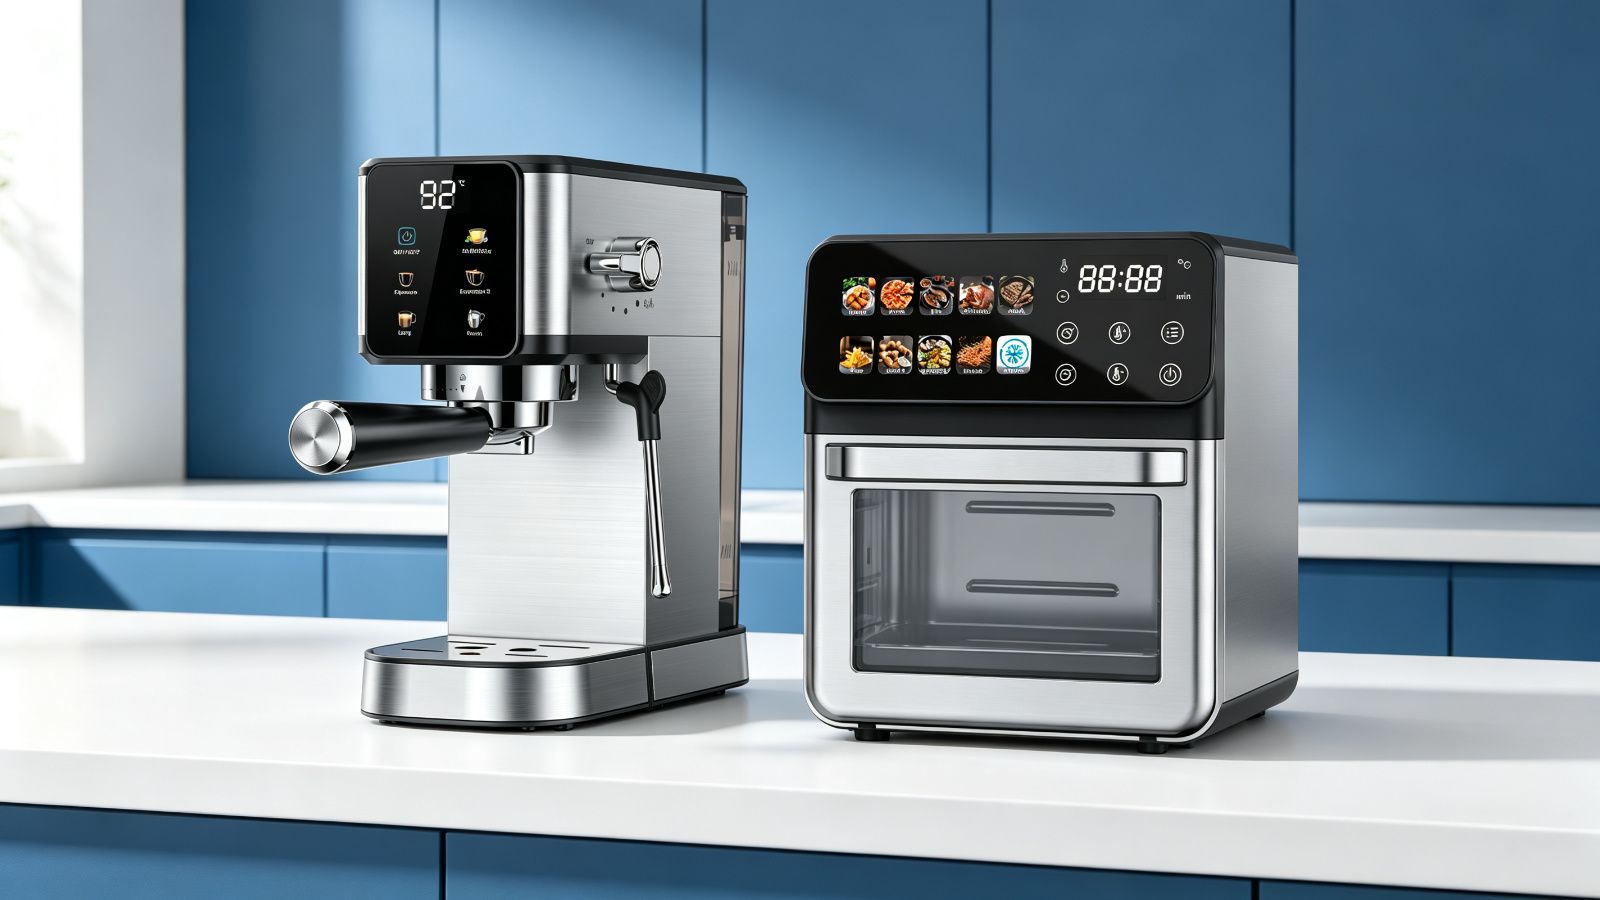
Walk into an Aldi or Lidl store in Germany, the UK, or Poland in mid-2026, and the kitchen appliance aisle tells you something that a trade show catalogue does not. Next to the branded espresso machine at €179 sits a private-label equivalent at €79. The air fryer shelf has a Silvercrest model at €39 next to a branded model at €89. The blender section offers a Lidl own-brand unit at €29 — below the FOB cost of some branded competitors. Discount retail private labels now account for 30–51% of grocery retail sales across major European markets, and the share is growing fastest in the small kitchen appliance category. For B2B importers, this shift changes which formats sell, at what price, through which channels, and against which competitors. This article maps what the discounter shift means for your sourcing strategy.
TL;DR — 30-Second Summary
- Private label now exceeds 30% of retail sales in every major Western European market. Switzerland leads at 51%, Spain at 44%, UK at 42%, Germany at 39%. Small kitchen appliances are one of the fastest-growing private-label categories within these markets (Wonnda, 2026).
- Discounters are running good-better-best private-label tiers. Aldi and Lidl no longer sell only the cheapest SKU. They now offer entry (€40–60), mid (€70–120), and premium own-brand (€130–200) kitchen appliances — competing directly with branded mid-market products.
- The discounter SKU creates a price ceiling for the entire category. When Lidl sells a private-label air fryer at €39, a branded importer cannot place a comparable model at €49 on the same retailer's shelf — and a specialty retailer competing with Lidl cannot price the same format at €89 without a feature story the discounter model lacks.
- Sections below: Market Data | Good-Better-Best Tiers | B2B Strategy | FAQ
Key Facts
Private-label market share in European grocery retail ranges from 28% in Poland to 51% in Switzerland, with Western European markets averaging 35–45%. Germany, the largest kitchen appliance market in Europe at 20.8% of revenue, operates at 39% private-label share. The UK, the fastest-growing major market, operates at 42%. In every major Western European market, more than one in three products sold through grocery and discounter channels carries a retailer-owned brand (Wonnda, 2026).
Aldi and Lidl are the two most influential private-label kitchen appliance retailers in Europe, and both are expanding. Aldi Süd and Aldi Nord together operate over 10,000 stores across Europe. Lidl operates over 12,000. Both chains are adding stores in Eastern Europe — Poland, Romania, Czech Republic — while upgrading their private-label kitchen appliance assortments in existing Western European markets. The Eastern European market guide covers the retail landscape in the region where discounter expansion is fastest.
Discounters are building good-better-best private-label tiers that compete with branded products across the price spectrum. The old model — one discounter SKU per category, priced at the absolute floor — has been replaced by a three-tier structure. Entry-level own-brand at €40–60 captures the price-sensitive buyer. Mid-tier own-brand at €70–120 competes directly with branded mid-market products on features and finish. Premium own-brand at €130–200 competes with specialty brands on design and material quality. A B2B importer whose product sits in the €70–120 band now competes against a discounter own-brand with comparable specifications and a lower retail price — because the discounter's supply chain eliminates one layer of importer margin.
PFAS regulation is accelerating the discounter shift by raising the compliance cost of entry-level branded products. EU REACH restrictions on PFAS — which include PTFE non-stick coatings — are pushing the cost floor of compliant kitchen appliances upward. Private-label supply chains, with their higher volumes and direct factory relationships, absorb compliance cost increases more efficiently than branded importers placing smaller, more frequent orders. The PFAS air fryer coating guide covers the regulatory timeline and coating alternatives.
The discounter channel creates volume opportunities for OEM suppliers who can meet the margin, compliance, and consistency requirements. Supplying a discounter private-label programme is a different business from supplying a branded importer. The volumes are larger, the per-unit margins are tighter, the compliance documentation requirements are more rigorous, and the production consistency expectation — every unit in every container identical to the approved sample — is non-negotiable. For OEM suppliers with the production capacity, in-house injection molding and tooling infrastructure, certification documentation, and production consistency to support discounter due diligence — across air fryers, blenders, coffee machines, and microwaves — the private-label channel represents the fastest-growing volume opportunity in European kitchen appliance retail.
How the Discounter Price Ceiling Works
When Lidl lists a private-label air fryer at €39, three things happen across the category.
First, the €39 SKU becomes the price anchor for every consumer walking into any retailer to buy an air fryer. The consumer may not buy the Lidl model. But they now measure every other air fryer against a €39 reference price. A branded model at €89 must justify a €50 premium — with a feature, a material, a certification, or a brand story that the discounter model lacks. A branded model at €49 that cannot articulate its €10 premium loses the comparison at the shelf.
Second, the discounter SKU captures the volume end of the market and holds it. The consumer who buys the €39 air fryer is not a lost sale for a premium brand — that consumer was never going to spend €89. But the consumer who would have spent €59 on an entry-level branded model, and now buys the €39 discounter model instead, is a lost sale. The discounter compresses the branded market upward — the remaining branded buyers are more demanding, more feature-conscious, and less price-sensitive. The branded volume that existed at the lower-middle price band migrates to private label.
Third, the discounter price ceiling travels across channels. A consumer who sees a €39 air fryer at Lidl and then browses Amazon sees an €89 model and asks: what makes this worth €50 more? If the Amazon listing cannot answer that question in the product title, the feature bullets, and the comparison table, the consumer buys the Lidl model on their next grocery trip. The discounter price ceiling affects every channel the consumer shops, not just the discounter aisle.
What this means for B2B importers. If your product occupies the €50–90 retail band — single basket digital air fryer, entry-level filter coffee machine, basic blender — and you cannot articulate a feature, material, certification, or brand story that justifies the premium over the discounter equivalent, your product is competing on price against a retailer that owns the shelf, controls the supply chain, and absorbs margin through grocery basket economics. You will lose that competition. The strategy is not to compete on price. It is to compete on something the discounter model lacks: a dual basket format, a GS certification, a fully automatic bean-to-cup mechanism, a PFAS-free ceramic coating, or a motor durability spec — anything the discounter SKU does not have, at a price the discounter SKU cannot reach.
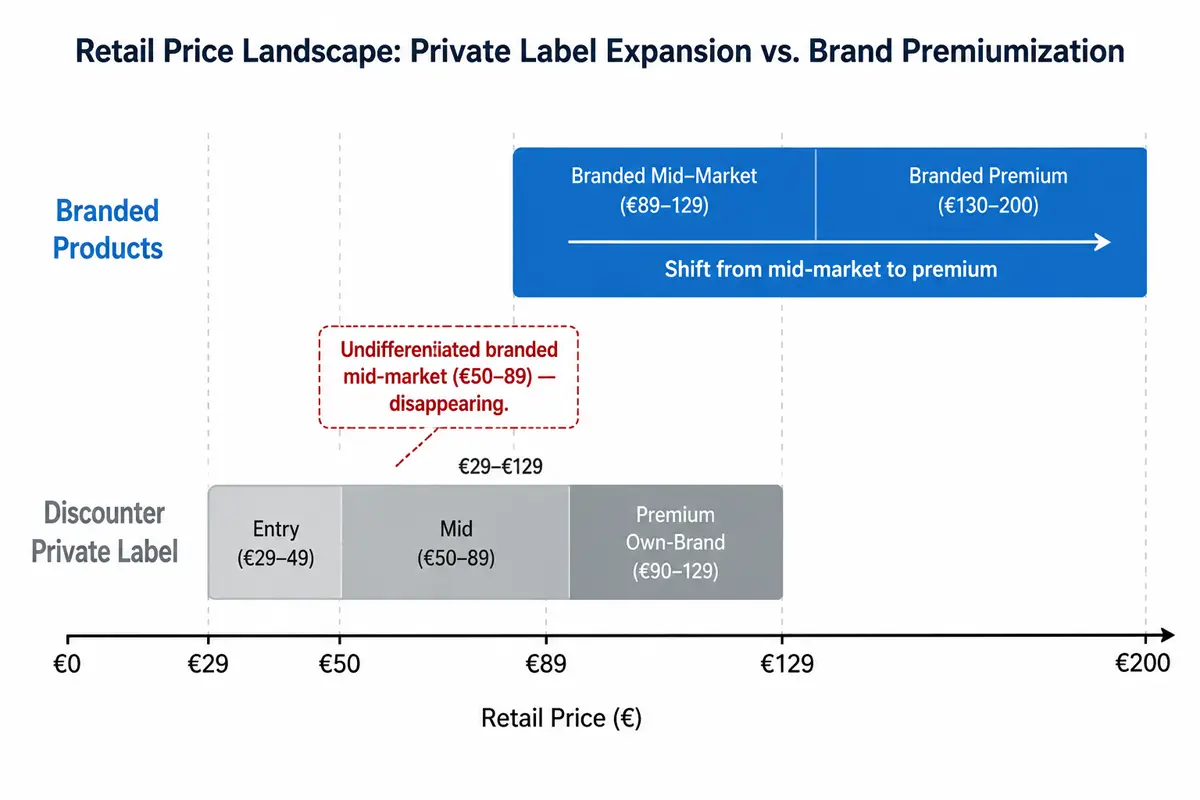
The discounter price ceiling in action. Private-label kitchen appliances occupy the €29–79 retail band with good-better-best tiers. Branded products are compressed into the €89+ premium tier where differentiation — format, certification, material, feature — must justify a €50+ premium over the discounter equivalent. The middle ground where undifferentiated branded products used to operate is disappearing.
Your 90-Day Discounter Strategy Plan
| If you are… | Do this in July | Then by October |
|---|---|---|
| A branded importer with products in the €50–90 retail band | Audit your product line. For every SKU in this band, ask: what feature, material, certification, or brand story justifies the premium over the discounter equivalent? | Eliminate or reposition any SKU that cannot answer the premium-justification question. Move surviving SKUs upmarket with a spec upgrade or downmarket with a cost restructure — undifferentiated middle ground is the losing position. |
| An importer considering supplying discounter private-label programmes | Request discounter vendor qualification requirements. Discounters require different documentation — typically higher-volume production capability proof, more detailed certification packages, and third-party social compliance audits — than branded retail buyers. | Submit vendor qualification for one discounter programme with one product category. Start with the format you can produce at the highest volume and most consistent quality. Discounter programmes reward consistency, not variety. |
| An OEM supplier with production capacity and certification infrastructure | Contact discounter private-label sourcing teams directly or through their appointed sourcing agents. Present your production capacity, certification documentation, and per-unit cost at discounter volumes — typically 5,000–20,000 units per SKU per order. | Complete vendor qualification and submit a product proposal for one discounter SKU. The qualification process typically takes 8–12 weeks from initial contact to approved vendor status. |
| A new importer placing first orders | Do not target the discounter channel. Discounter programmes require production volumes, compliance infrastructure, and supply chain consistency that a first-order importer does not yet have. | Target specialty retail, e-commerce, or regional chains where your differentiation story — format, feature, certification — can command a premium over the discounter price ceiling. Build volume and compliance capability first, then approach discounters in 2027–2028. |
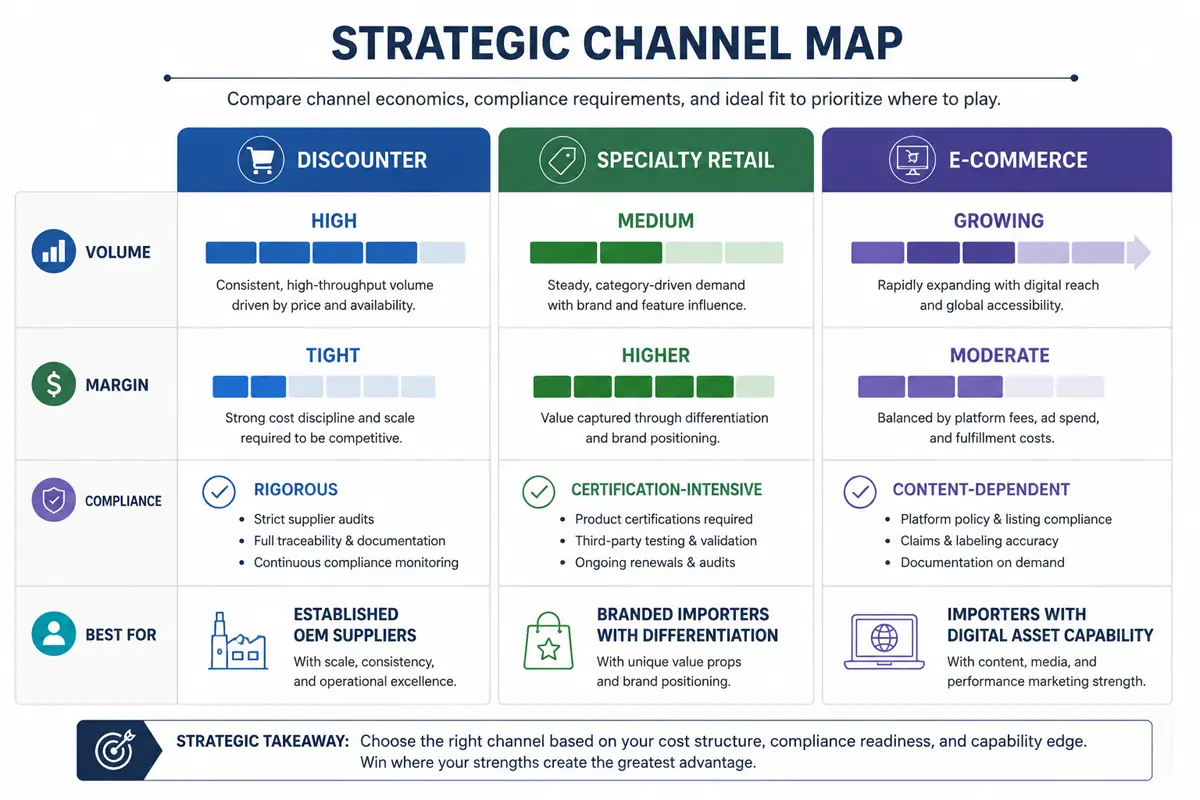
Three channels, three strategies. Discount retail = volume, tight margin, rigorous compliance — for established OEM suppliers. Specialty retail = premium, higher margin, certification-intensive — for branded importers with a differentiation story. E-commerce = fastest-growing channel, content-dependent — for importers with digital asset capability. Choose the channel that matches your operational strength, not the one with the highest volume number.
📊 From APEXDURA's Export Desk
In conversations with European buyers during the first half of 2026, the importers who are adapting to the discounter shift share one characteristic: they have stopped competing on price against retailers who own the shelf. Instead, they are competing on format — dual basket instead of single basket, bean-to-cup instead of filter, PFAS-free ceramic instead of PTFE — and targeting channels where the discounter private-label SKU is not the reference price. The importers who are struggling share a different characteristic: their product is the same format, with the same features, at a slightly higher price, sold through the same channel as the discounter equivalent. The discounter shift does not eliminate the market for branded kitchen appliances. It eliminates the market for undifferentiated ones.
Frequently Asked Questions
Should I try to supply Aldi or Lidl's private-label kitchen appliance programme?
If you have production capacity exceeding 5,000 units per SKU, full CE, RoHS, REACH, and LFGB documentation, and a track record of consistent production quality across multiple container shipments, yes — the discounter private-label channel is the highest-volume growth opportunity in European kitchen appliance retail. If you are placing your first or second order, no — build volume, compliance capability, and production consistency first, then approach discounter programmes in 12–24 months.
How do I differentiate my product from a discounter private-label equivalent?
Add something the discounter SKU does not have. A format the discounter does not offer — dual basket instead of single basket air fryer, bean-to-cup instead of filter coffee machine. A certification the discounter SKU does not carry — GS for German specialty retail. A material the discounter SKU does not use — PFAS-free ceramic coating instead of PTFE. A spec the discounter SKU does not publish — motor rated lifespan in hours instead of wattage. Differentiation lives in the spec sheet, not the marketing copy.
Will the discounter shift spread to Eastern Europe?
It already is. Aldi and Lidl are both expanding store counts in Poland, Romania, and Czech Republic. Private-label share in Poland is 28% and rising. Eastern European consumers are more price-sensitive than Western European consumers, which accelerates discounter adoption. The Eastern European market guide covers the retail dynamics by country.
Can I sell the same product to a discounter and a specialty retailer?
No. If the same SKU appears at €39 at Lidl and €79 at a specialty retailer, the specialty retailer drops the SKU after the first consumer complaint about the price difference — and that complaint arrives within days of the Lidl listing going live. Differentiate by model number, by bundled accessory, by colourway, or by format variant. The private label launch guide covers SKU differentiation strategies for multi-channel importers.
What is the margin structure of a discounter private-label programme?
Expect to operate on 8–15% importer margin versus 20–35% for a branded product sold through specialty retail. The volume compensates — a discounter order of 10,000 units at 10% margin generates the same gross profit as a specialty retail order of 3,300 units at 30% margin — but the working capital requirement is larger, the payment terms are longer, and the production consistency expectation is higher. Discounter programmes are a volume-and-efficiency business. Branded specialty retail is a margin-and-differentiation business. Do not confuse the two.
Review your product line against the discounter price ceiling.
Send us your current SKU list and target retail channels — we'll confirm which APEXDURA formats, certifications, and specifications can support a discounter-channel or a premium-differentiation strategy within 24 hours.
Request Channel Strategy Review →
Source Kitchen Appliances with APEXDURA
APEXDURA is the international brand of Zhongshan Zhenmei Electrical Appliance Co., Ltd. — 16 years of OEM/ODM manufacturing experience, 500,000 units annual output, and 0.8% defect rate across 12 production lines.
Multi-channel sourcing strategy supported at RFQ stage:
- ✅ Discounter-ready production volumes with full CE, RoHS, REACH, LFGB, and GS documentation — per-SKU compliance packages confirmed before production
- ✅ Premium-differentiated formats — dual basket air fryers, fully automatic coffee machines, PFAS-free ceramic coatings, inverter microwaves — for specialty retail and e-commerce channels
- ✅ SKU differentiation support — distinct model numbers, accessory bundles, colourways, and packaging variants to prevent channel conflict
- ✅ Per-unit cost modelling at discounter volumes (5,000–20,000 units) versus specialty retail volumes (500–3,000 units) — transparent pricing, no hidden reformulation fees
Every enquiry receives a response within 24 hours, with channel strategy recommendations, product availability, certification status, MOQ, and lead time confirmed.
📧 Email: devin@zszhenmei.com 📱 WhatsApp: +86 136 1272 5240 🔗 Request a Sourcing Quote →