


Chinese Kitchen Appliance Brands Move Upmarket: What It Means for B2B Importers
Chinese Kitchen Appliance Brands Move Upmarket: What It Means for B2B Importers
For a decade, the B2B importer strategy for competing with Chinese kitchen appliance brands in Europe was simple: Chinese brands occupied the entry-level shelf at €29–49, and European private-label and branded importers occupied the mid-to-premium shelf at €69–199. That segmentation is collapsing. Midea now sells a portable air conditioner at €999 that sold out across Europe during the June 2026 heatwave. Xiaomi's European appliance sales grew 600% in the first half of 2026. Chinese small appliance brands are no longer competing only on price. They are competing on features, design, energy ratings, and retail shelf placement — the same territory that B2B private-label and branded importers have treated as their own. This article maps what the Chinese brand upmarket shift means for your sourcing strategy in H2 2026.
TL;DR — 30-Second Summary
- Chinese brands are expanding from entry-level into premium European price bands. Midea, Xiaomi, and Haier are investing in European-localised product design, higher-spec components, and brand marketing — competing directly with mid-market European brands, not just at the discounter shelf.
- The competitive gap is closing on features, not just price. Chinese brands now ship products with inverter motors, PFAS-free coatings, smart connectivity, and A-rated energy labels — the same specification sheet that European private-label importers use to differentiate from discounter own-brands.
- B2B importers need a new competitive strategy. Competing against a discounter private label required a format or certification upgrade. Competing against a Chinese brand with comparable specs, a brand identity, and a lower retail price requires a different playbook.
- Sections below: The Shift | What Changed | Competitive Strategy | FAQ
Key Facts
Chinese small appliance brands are the fastest-growing competitor segment in European retail, with growth rates significantly outpacing European branded and private-label competitors. NIQ data for the July 2024–June 2025 period shows Chinese brands outperforming all other competitor categories in European small appliance growth. The growth is concentrated in vacuum cleaners, air treatment, and small kitchen appliances — air fryers, coffee machines, and blenders among them (NIQ Home Appliances Outlook, 2026).
Midea's PortaSplit portable air conditioner — retailing at approximately €999 — sold over 100,000 units in Europe in H1 2026. Production is scheduled through August 2026 to meet demand. The product's success is not a price story — €999 is a premium price point for a portable AC. It is a product-design story: the PortaSplit addresses the European housing constraint of drill-free installation, a feature European competitors did not offer at launch (Xinhua, July 2026).
Xiaomi reported a 600% increase in European fan and small appliance sales in the first half of 2026. The growth is driven by a combination of aggressive retail expansion, competitive pricing on feature-rich products, and Xiaomi's existing European smartphone brand recognition transferring to the appliance category (Xinhua, July 2026).
Chinese brands are investing in European-localised R&D, not just exporting China-market products with different plugs. The pattern is shifting from "export adaptation" — the minimum changes required to sell a China-market product in Europe — to "market-specific development" — products designed from the ground up for European consumer preferences, housing constraints, energy efficiency expectations, and regulatory requirements. This investment narrows the feature gap that European private-label importers have relied on to justify their price premium over entry-level alternatives.
The competitive shift does not only affect branded importers. It affects OEM suppliers whose European customers are Chinese brands. A European B2B importer sourcing air fryers from a Guangdong factory is competing for that factory's production capacity, engineering attention, and component allocation against the factory's Chinese brand customers, who may place larger orders, offer longer contract commitments, and represent the factory's own-market growth strategy. The supplier relationship that European importers have relied on for cost-competitive access to Chinese manufacturing is the same supplier relationship that Chinese brands are deepening for their European expansion.
The Shift: From Entry-Level to Premium
The Chinese brand trajectory in European kitchen appliances follows a pattern that Japanese and Korean brands executed in consumer electronics a generation ago. The first phase — price-led market entry at the bottom of the category — has been underway for a decade. The second phase — feature parity at competitive prices in the mid-market — is happening now. The third phase — brand-led premium positioning with European-localised design — is visible in early examples and likely to accelerate through 2027–2028.
Three structural changes are driving the shift from phase one to phase two.
European-localised product development. Chinese brands are no longer modifying China-market products for Europe. They are developing products for European consumers from the specification stage. This means products designed for European housing sizes, European energy label expectations, European food-contact material requirements, and European consumer preferences for quieter operation, higher energy efficiency, and repairability. The PFAS-free coating shift that Cosori addressed with a ceramic-coated air fryer in January 2026 is an example — the product was developed for the European and North American regulatory trajectory, not adapted from a China-market model.
Brand investment at European retail scale. Xiaomi, Midea, and Haier are investing in European brand marketing, retail partnerships, and after-sales infrastructure — the same fixed-cost investments that European private-label importers make to secure shelf placement. A European retail buyer choosing between a private-label air fryer from a B2B importer and a branded air fryer from Midea compares two products with comparable specifications, from companies with comparable European infrastructure. The private-label importer's historical advantage — "we handle the compliance, the logistics, and the retail relationship" — is matched by a Chinese brand that handles the same three functions internally.
Production priority at shared factories. Many Chinese brands and European B2B importers source from overlapping supplier bases in Guangdong and Zhejiang. When production capacity is constrained — as it is during the July–October peak season documented in the Q3 production slot planning guide — the factory allocates capacity to its largest, most reliable, and most strategically important customers. A Chinese brand placing a 50,000-unit order with a 12-month commitment receives production priority over a European importer placing a 1,000-unit trial order. The supplier relationship that European importers rely on for cost-competitive access is the same relationship that Chinese brands are deepening for their own European growth.
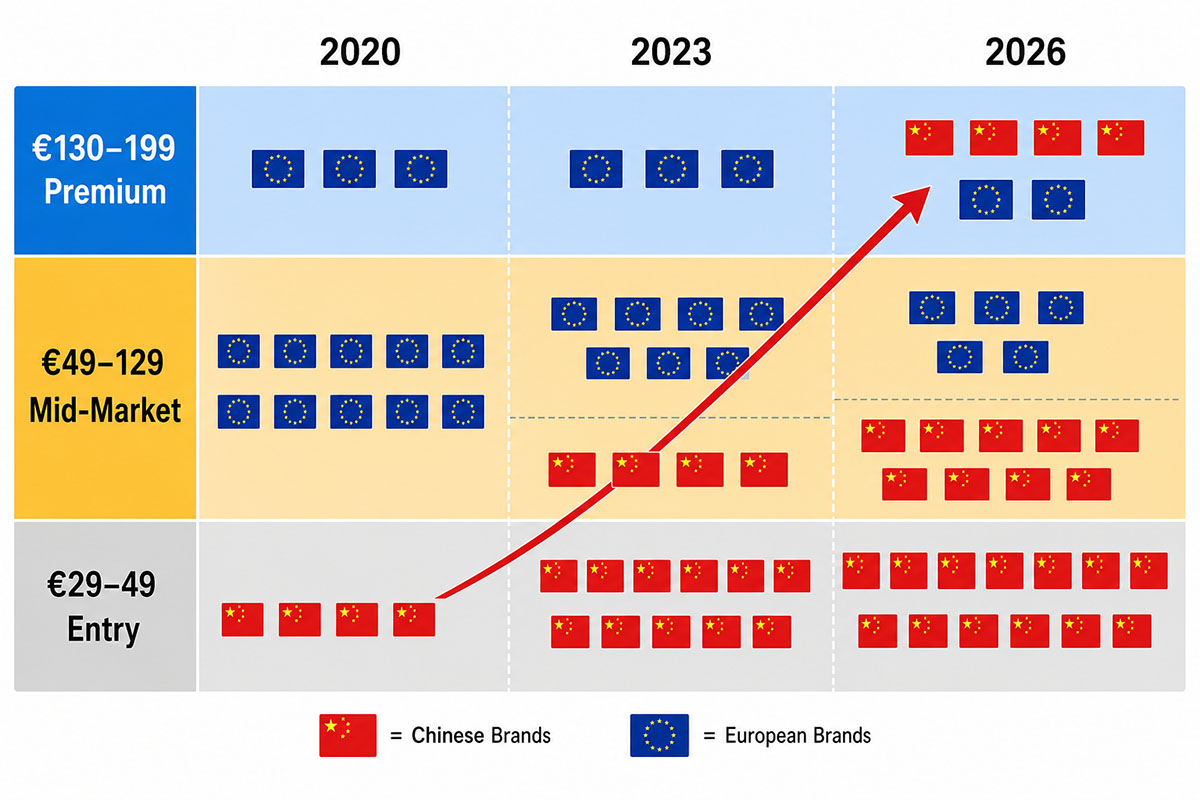
The competitive shift in one chart. Chinese brands previously occupied the €29–49 entry band. In 2026, they compete across the €49–199 mid-to-premium bands — the same territory European private-label and branded importers occupy. The price-based competitive moat that European importers relied on is narrowing to a feature-and-brand moat.
Your 90-Day Competitive Strategy Plan
This week: Open the website of one Chinese brand active in your product category — Midea, Xiaomi, Haier, or Cosori. Compare their European-market product specifications against your current order specification. If their spec sheet matches or exceeds yours at a lower retail price, your Q4 order needs a specification upgrade before the PO goes out.
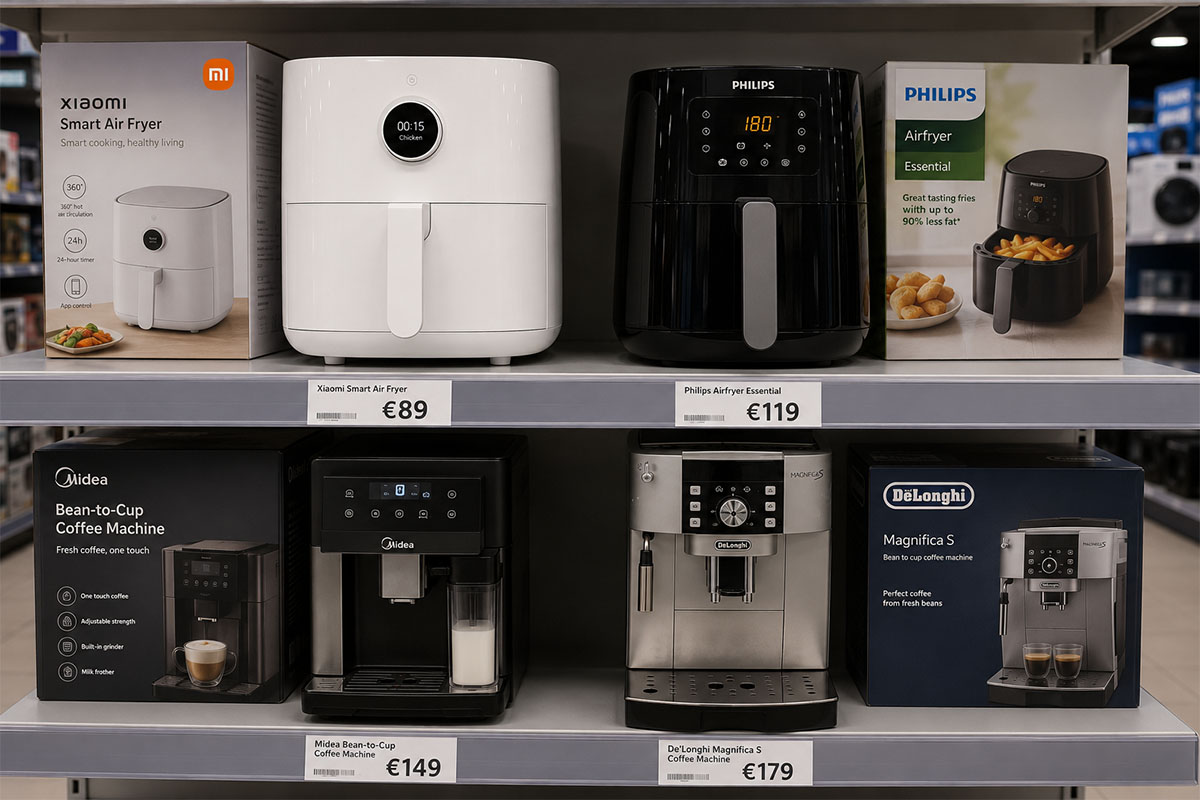
A European retail shelf in 2026. Chinese-brand kitchen appliances are no longer confined to the bottom shelf. Midea, Xiaomi, and Haier products occupy eye-level shelf positions at €79–199 — the same height and price as established European brands. The shelf tells the competitive story before the specification sheet does.
📊 From APEXDURA's Export Desk
In supplier conversations with European buyers during the first half of 2026, the importers who have adjusted their competitive strategy in response to the Chinese brand upmarket shift share one characteristic: they have stopped competing on the specification sheet alone. They are competing on one additional element — certification depth, retail buyer economics, after-sales infrastructure, format differentiation, or brand story — that the Chinese-brand equivalent does not offer or cannot document at the same level. The importers who have not adjusted are competing on the same specifications at a higher retail price, and they are losing shelf positions one retail buyer conversation at a time.
Frequently Asked Questions
Are Chinese brands really competing at premium price points, or is this limited to a few categories?
The shift is most advanced in air treatment and vacuum cleaners, where Chinese brands already hold significant premium-market share. In small kitchen appliances, the shift is underway but uneven. Air fryers and portable cooking appliances are further along than coffee machines and blenders, where European brand heritage still carries consumer preference weight. But the trajectory is consistent across categories, and the investment in European-localised R&D suggests the shift will accelerate, not stall.
Should I stop sourcing from Chinese factories?
No. Chinese manufacturing remains the most competitive, capable, and well-documented OEM supply base for kitchen appliances. The strategic question is not where you source. It is what you source — the product specification, the certification package, the format differentiation — and how you position it against a competitor that sources from the same factory base and sells through the same retail channels.
How do I differentiate my product from a Chinese brand with comparable specs?
Add something the Chinese-brand product does not have or cannot document. A GS certification for DACH retail, a PFAS-free coating with dated test reports, a motor durability spec published in hours, a spare-parts catalogue with per-unit pricing — any documented claim the Chinese-brand product cannot match. Differentiation lives in the spec sheet and the certification file, not in the brand story.
Will the Chinese brand upmarket shift affect the discounter channel?
The discounter channel — Aldi, Lidl, and private-label own-brands — operates on a different competitive dynamic. Discounter private labels compete primarily on price within the discounter's own shelf, not against branded products in other channels. Chinese brands are moving upmarket toward branded retail, not downmarket toward discounter own-brand supply. The two competitive dynamics coexist but operate in different retail segments.
Review your product positioning against the Chinese brand competitive shift.
Send us your current product specifications and target retail price band — we'll confirm which APEXDURA differentiators (certifications, format options, material specifications, documentation depth) can strengthen your competitive position within 24 hours.
Request Competitive Strategy Review →
Source Differentiated Kitchen Appliances with APEXDURA
APEXDURA is the international brand of Zhongshan Zhenmei Electrical Appliance Co., Ltd. — 16 years of OEM/ODM manufacturing experience, 500,000 units annual output, and 0.8% defect rate across 12 production lines.
Competitive differentiation confirmed at RFQ stage:
- ✅ Format differentiation — dual basket air fryers, bean-to-cup coffee machines, masticating juicers, inverter microwaves — formats that Chinese-brand product lines do not always offer
- ✅ Certification depth — GS, LFGB, CE, RoHS, REACH, ErP, PED — documented with dated test reports by model number, provided within 48 hours
- ✅ Specification transparency — motor rated lifespan in hours, continuous runtime rating, PFAS-free material declarations, spare-parts catalogue with per-unit pricing
- ✅ Production priority — dedicated production lines for long-term B2B partner orders, not shared capacity with brand-production runs
Every enquiry receives a response within 24 hours, with competitive positioning analysis, product availability, certification status, MOQ, and lead time confirmed.
📧 Email: devin@zszhenmei.com 📱 WhatsApp: +86 136 1272 5240 🔗 Request a Sourcing Quote →