


EU Tariffs and Carbon Costs: The 2026 Trade Cost Landscape for Kitchen Appliance Importers
EU Tariffs and Carbon Costs: The 2026 Trade Cost Landscape for Kitchen Appliance Importers
Two trade cost mechanisms — one a punitive tariff, the other a carbon price — are reshaping the landed cost calculation for kitchen appliance imports into Europe in mid-2026. The EU imposed a flat 79% anti-dumping duty on Chinese ceramic tableware and kitchenware in February 2026, and a German importer filed an appeal against it in July. Separately, the Carbon Border Adjustment Mechanism expanded its scope on January 1, 2026 to cover kitchen appliances with steel or aluminum content exceeding 30% of the product — adding a carbon certificate cost of approximately €80–100 per tonne of embedded CO₂ to every affected import. Neither measure currently applies to the full range of small kitchen appliances — air fryers, blenders, and coffee machines are not ceramic tableware, and most do not exceed the 30% metal-content threshold. But the direction of trade cost policy is unambiguous, and importers who model the trajectory now will recognise the next cost increase before it arrives, not after it appears on their customs declaration.
TL;DR — 30-Second Summary
- A 79% anti-dumping duty on Chinese ceramic tableware and kitchenware is now in force, and a German importer (Holst Porzellan) filed an appeal at the EU General Court in July 2026. The duty signals a hardening EU trade defence posture toward Chinese-manufactured kitchen products.
- CBAM carbon tariffs now apply to kitchen appliances with steel or aluminum content exceeding 30% — including ovens, microwaves, and some larger countertop appliances. Importers must declare embedded carbon emissions and purchase certificates at approximately €80–100 per tonne of CO₂.
- Neither measure currently targets small kitchen appliances directly, but the policy trajectory — anti-dumping duties expanding from tableware to adjacent categories, carbon tariffs starting with steel-intensive products and widening scope — points toward broader application over the next 2–4 years.
- Sections below: Anti-Dumping | CBAM | Landed Cost Impact | FAQ
Key Facts
The EU imposed a flat 79% anti-dumping duty on Chinese ceramic tableware and kitchenware in February 2026, replacing previous individual company rates of 13.1%–36.1%. The European Commission justified the increase by citing severe market distortions in China that made individual company duty rates unworkable. In July 2026, German importer Holst Porzellan filed an appeal (Case T-274/26) at the EU General Court challenging the Commission's decision (EU Official Journal, February 2026; MLex, July 2026).
The CBAM carbon border adjustment mechanism expanded on January 1, 2026 to include kitchen appliances with steel or aluminum casing and component content exceeding 30% of the product. Ovens, microwaves, and some larger countertop appliances fall within scope. Importers must declare the CO₂ emissions embedded in the production of the covered steel and aluminum components and purchase carbon certificates at the prevailing EU Emissions Trading System price — approximately €80–100 per tonne of CO₂ in mid-2026 (TradeDaas, July 2026).
The anti-dumping duty and CBAM are separate mechanisms with different triggers, different calculation methods, and different product coverage — but they share a common policy direction. Anti-dumping duties target products sold below normal value in the exporting country. CBAM targets the carbon intensity of production regardless of the product's selling price. Both increase the landed cost of imports from higher-carbon, lower-cost manufacturing economies — which describes the majority of Chinese kitchen appliance production.
The 79% anti-dumping duty on ceramic kitchenware does not directly apply to small electric kitchen appliances — air fryers, blenders, coffee machines. The product scope is defined by CN codes for ceramic tableware and kitchenware (6911 10 00, 6912 00 21, etc.). Small electric kitchen appliances fall under different tariff codes. But the policy logic — a shift from company-specific duty rates to flat high-rate duties justified by market distortion claims — is transferable to any product category where Chinese imports hold a dominant share.
CBAM carbon certificate costs are passed through the supply chain to the importer of record in the EU. A non-EU manufacturer does not pay CBAM. The EU-based importer declares the embedded emissions and purchases the certificates. Importers who cannot obtain verified carbon emissions data from their suppliers must use default values — which are set at the highest emissions intensity for the product category, maximising the certificate cost — until actual verified data is available.
The 79% Anti-Dumping Duty: A Leading Indicator
The anti-dumping duty on ceramic tableware and kitchenware is not, by itself, a direct cost increase for most readers of this article. The product scope covers ceramic plates, bowls, and kitchen utensils — not electric air fryers, coffee machines, or blenders. But the duty structure and the justification behind it are leading indicators for any importer sourcing kitchen products from China.
Three characteristics of this case matter beyond the immediate product scope.
The shift from individual rates to a flat high rate. Previous anti-dumping duties assigned different rates to different Chinese manufacturers — 13.1% for one company, 36.1% for another — based on their demonstrated cooperation with the investigation and the assessed dumping margin for their specific production. The February 2026 decision replaced individual rates with a single 79% rate for all exporters, justified by the Commission's finding that market distortions in China made individual rate calculations unreliable. This is a structural change in how the EU applies trade defence instruments, not a one-off product-specific decision. Any future anti-dumping investigation into a Chinese-manufactured product category can apply the same logic and arrive at the same flat-rate outcome.
The appeal confirms the rate is being enforced, not suspended. Holst Porzellan's appeal at the EU General Court challenges the legality of the Commission's decision. Crucially, an appeal does not suspend the duty — importers continue to pay 79% while the case proceeds. The appeal process typically takes 18–24 months. Importers with affected products cannot wait for the appeal outcome before adjusting their sourcing strategy.
The product scope boundary is porous. Ceramic kitchenware and small electric kitchen appliances are different product categories with different CN codes, different supply chains, and different competitive dynamics. But from a trade policy perspective, the distinction between a ceramic mixing bowl and a plastic-housed electric stand mixer is a tariff classification line, not a policy firewall. The EU-China trade tension dynamic that produced a 79% anti-dumping duty on one Chinese kitchen product category can, with the same logic and the same procedural mechanism, produce a similar duty on another.
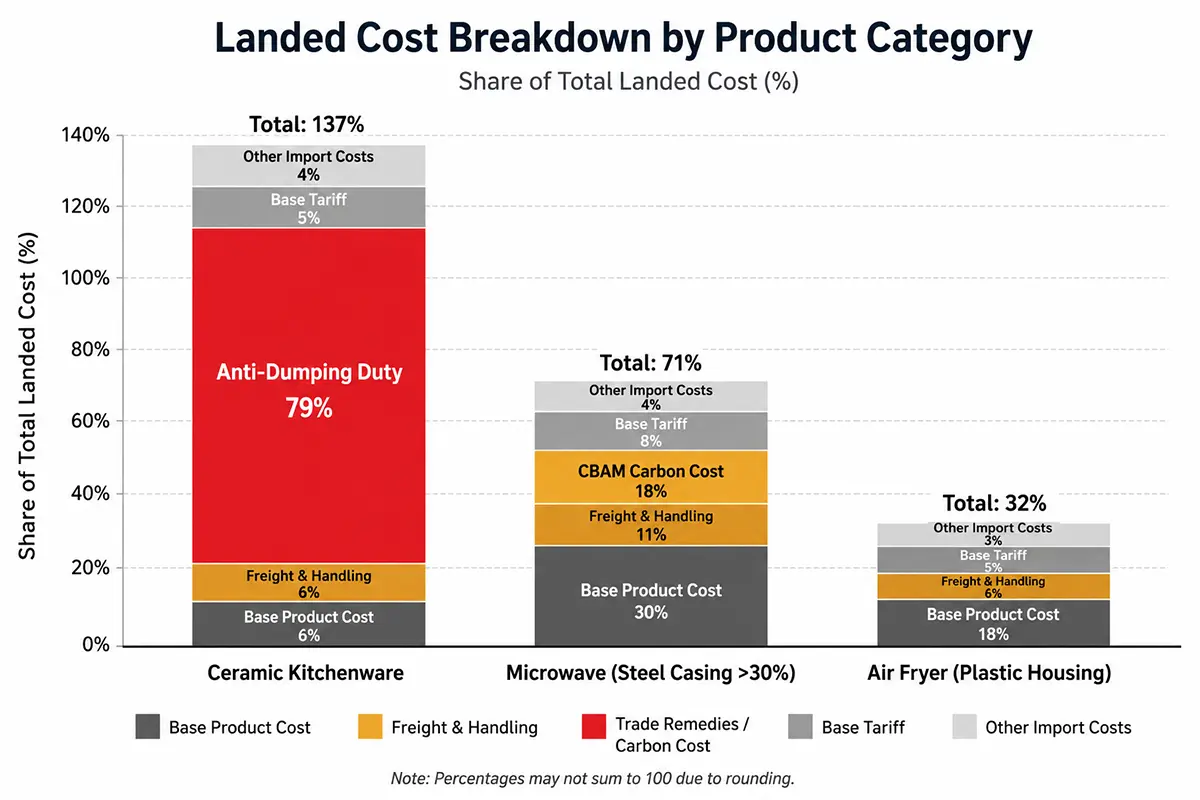
The 2026 trade cost stack. Base FOB cost + standard EU tariff (2–4% for most kitchen appliances) + anti-dumping duty (79% for ceramic kitchenware, not applicable to small electric appliances) + CBAM carbon certificates (€80–100/tonne CO₂ for steel/aluminum-intensive products). Not every cost applies to every product — but the layering of trade cost mechanisms is expanding, not contracting, and the products not covered today are the products under review tomorrow.
CBAM: The Carbon Cost That Compounds Every Year
The Carbon Border Adjustment Mechanism operates differently from an anti-dumping duty. It is not a fixed percentage added to the customs value. It is a certificate purchase obligation linked to the EU Emissions Trading System carbon price, which fluctuates — and which the EU's climate policy trajectory pushes upward over time.
For a kitchen appliance importer, CBAM affects products where steel or aluminum accounts for more than 30% of the product by weight. A microwave with a steel cavity, a steel outer casing, and a steel door frame almost certainly exceeds this threshold. A countertop oven with a steel interior and aluminum door may exceed it. An air fryer with a plastic housing and a stainless steel basket — depending on the basket weight relative to the total product weight — may or may not exceed it.
The importer's obligation is to declare the verified embedded carbon emissions for the covered steel and aluminum components. If verified data from the supplier is not available — which describes the situation for most China-based OEM suppliers in mid-2026 — the importer must use default values set at the highest emissions intensity for the product category. Using default values maximises the certificate cost. Obtaining verified emissions data from the supplier minimises it.
What this means for your Q4 and 2027 orders. For every product in your line that contains steel or aluminum, ask your supplier two questions. First, does the steel or aluminum content exceed 30% of the product weight? If yes, the product is in CBAM scope. Second, can the supplier provide verified carbon emissions data for the steel and aluminum components? If no, your customs declaration will use default values at the maximum emissions intensity — and your landed cost will be higher than an importer whose supplier provides verified data. The kitchen appliance logistics guide covers import documentation requirements, of which CBAM declarations are now one component.
Your 90-Day Trade Cost Action Plan
| If you are… | Do this in July | Then by October |
|---|---|---|
| An importer of ceramic kitchenware from China | Confirm whether your products fall within the CN codes subject to the 79% anti-dumping duty. If yes, the duty applies at customs clearance regardless of your supplier relationship. | Model three scenarios: absorb the duty (margin impact), pass through to retail price (volume impact), or shift sourcing to a non-Chinese supplier (transition cost). The appeal does not suspend the duty. |
| An importer of microwaves, ovens, or steel/aluminum-intensive appliances | Request component weight breakdown from your supplier. Determine whether steel + aluminum exceeds 30% of total product weight. If yes, CBAM applies. | Request verified carbon emissions data for steel and aluminum components. If unavailable, budget for default-value certificate costs — approximately €80–100 per tonne of embedded CO₂ at mid-2026 carbon prices — and build this into your Q1 2027 landed cost model. |
| An importer of small plastic-housed appliances | Verify that steel and aluminum content is below 30%. Document the weight breakdown in your CE technical file to support a future CBAM exemption claim if your product is queried at customs. | Monitor the CBAM product scope expansion. The current threshold and product coverage will widen over time. A product outside scope today may be inside scope in 2027 or 2028. |
| Any importer sourcing from China | Add one trade cost scenario to your Q4 planning: a flat-rate anti-dumping duty investigation opened against your product category. What rate would make your current sourcing model unviable? | Identify a non-Chinese alternative supplier for one product category — not to shift volume immediately, but to have a qualified option if a trade measure is announced. |
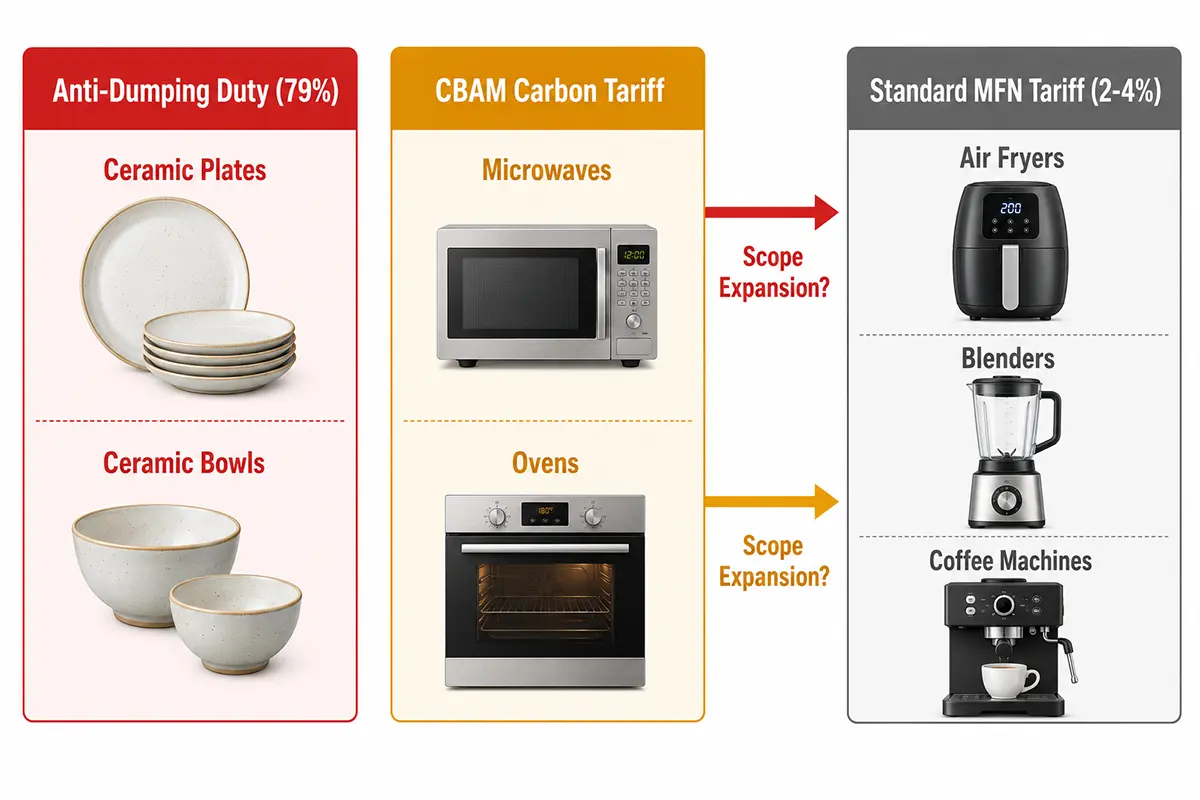
Trade cost coverage by product category in 2026. Ceramic kitchenware: anti-dumping duty (79%). Steel/aluminum-intensive appliances: CBAM carbon certificates. Air fryers, blenders, coffee machines: standard MFN tariff only (2–4%). The grey area — products not yet covered — is where the next trade measure is most likely to appear.
📊 From APEXDURA's Export Desk
In trade cost conversations with European buyers during the first half of 2026, the importers who have adjusted their landed cost models to include anti-dumping and carbon tariff scenarios share one characteristic: they treat trade costs as a structural input to sourcing decisions, not a one-time customs surprise. They request product weight breakdowns, verified emissions data, and CN code classifications at the RFQ stage — alongside the FOB price and the certification package. The importers who have not adjusted treat trade costs as something the customs broker handles after the shipment arrives. The difference between these two approaches is approximately 79% on ceramic kitchenware and €80–100 per tonne of CO₂ on steel-intensive appliances — applied to every container that clears customs after the measure takes effect.
Frequently Asked Questions
Does the 79% anti-dumping duty apply to electric air fryers, blenders, or coffee machines?
No. The duty applies to ceramic tableware and kitchenware classified under specific CN codes (6911 10 00, 6912 00 21, and related codes). Small electric kitchen appliances are classified under different tariff headings and are not within the product scope of this anti-dumping measure. The policy significance is the duty's structure — a flat high rate replacing individual company rates — which can be applied to any future anti-dumping investigation regardless of product category.
How do I know if my product exceeds the 30% steel/aluminum threshold for CBAM?
Request a component weight breakdown from your supplier. Calculate steel and aluminum weight as a percentage of total product weight. If the combined weight exceeds 30%, CBAM applies. Document the calculation in your CE technical file. If the product is queried at customs, the documented weight breakdown is your evidence for either compliance or exemption.
What happens if I cannot get verified carbon emissions data from my supplier?
Your customs declaration will use default values set at the highest emissions intensity for the product category. This maximises your CBAM certificate cost. The incentive structure is designed to reward importers who obtain verified supplier data and penalise those who do not. Building CBAM data requirements into your supplier contract is the structural fix.
Will the CBAM product scope expand to cover more kitchen appliances?
Yes. The CBAM regulation is designed to expand coverage progressively. The current scope — steel, aluminum, cement, fertilisers, electricity, and hydrogen — is the starting point. The European Commission is required to review and propose scope extensions. Kitchen appliances with lower metal content, plastic-housed products, and eventually products with significant embedded carbon in any material are plausible candidates for future inclusion. The ESPR Digital Product Passport will eventually provide the product-level carbon data that makes broader CBAM coverage administratively feasible.
Can the Holst Porzellan appeal get the 79% duty overturned?
The appeal challenges the legality of the Commission's decision to impose a flat rate instead of individual company rates. If successful, the Commission would be required to reassess the duty methodology — but would not necessarily be required to eliminate the duty. Importers with affected products should model the duty as a continuing cost and treat a successful appeal outcome as a potential future cost reduction, not a current planning assumption.
Model your product line's trade cost exposure for H2 2026.
Send us your product categories, materials composition, and target markets — we'll confirm APEXDURA product weight breakdowns, verified emissions data availability, and CN code classifications within 24 hours.
Request Trade Cost Assessment →
Source Kitchen Appliances with Trade-Cost-Transparent APEXDURA
APEXDURA is the international brand of Zhongshan Zhenmei Electrical Appliance Co., Ltd. — 16 years of OEM/ODM manufacturing experience, 500,000 units annual output, and 0.8% defect rate across 12 production lines.
Trade cost documentation confirmed at RFQ stage:
- ✅ Product weight breakdown by material — steel, aluminum, plastic, glass, electronic components — documented per model
- ✅ CN code classification confirmed for every product — verify which trade measures apply before the shipment leaves the factory
- ✅ Carbon emissions data for steel and aluminum components — verified supplier data to minimise CBAM certificate costs, not default values
- ✅ EU authorised representative documentation — you are not the default trade cost obligor for customs declarations, anti-dumping duty assessments, or CBAM certificate purchases
Every enquiry receives a response within 24 hours, with trade cost classification, material composition data, certification status, MOQ, and lead time confirmed.
📧 Email: devin@zszhenmei.com 📱 WhatsApp: +86 136 1272 5240 🔗 Request a Sourcing Quote →