


Europe Kitchen Appliances Mid-2026: Three Signals for Q4 Sourcing
Europe Kitchen Appliances Mid-2026: Three Signals for Q4 Sourcing
The European small kitchen appliance market reached approximately USD 9.5 billion in the first half of 2026, growing at 4.7% annually (Grand View Research, 2026). But the headline number hides three category-level shifts that should change what you order, in what quantity, and for which channel in Q4. Here are the three numbers that matter — and the sourcing decision each one should trigger.
TL;DR — 30-Second Summary
- 6.8%: Air fryer CAGR, the fastest-growing category — but the growth is moving from single basket to dual basket and XL formats. If your Q4 air fryer order is still dominated by entry-level single basket units, you are ordering for yesterday's market.
- 16.4%: Coffee machines' share of total European small kitchen appliance revenue, making it the single largest category by value — and premiumisation toward bean-to-cup is accelerating faster than most importers' product lines are adjusting.
- 35-40%: Online's share of EU kitchen appliance sales, up from 25% in 2020 and growing at 5.6% annually. If your packaging, product content, and channel strategy were built for physical retail, Q4 is the deadline to add an online-ready SKU.
- Sections below: Signal 1 — Air Fryer Format Shift | Signal 2 — Coffee Premiumisation | Signal 3 — Online Channel | Q4 Order Checklist | FAQ
Key Facts
The European small kitchen appliance market is projected to grow from USD 9.06 billion in 2025 to USD 13.1 billion by 2033, a 4.7% CAGR. Germany holds the largest country share at 20.8% of revenue. The UK is the fastest-growing major market by CAGR. Air fryers lead product-level growth at 6.8%, coffee machines lead revenue share at 16.4%, and online is the fastest-growing channel at 5.6%+ (Grand View Research, 2026).
Air fryer growth is moving from single basket to dual basket and XL formats. Groupe SEB launched XL-capacity dual basket air fryers in 2024. De'Longhi entered the category with the design-led Vivaci range. The entry-level single basket segment is now crowded, with discounter private labels exerting price pressure below €50 retail. The growth — and the margin — has moved to dual basket, XL, and multi-function formats.
Coffee machine premiumisation toward bean-to-cup is accelerating, while pod systems face sustainability headwinds. Fully automatic espresso machines are the fastest-growing coffee sub-segment, driven by sustained at-home coffee culture and high-street café price inflation. Pod and capsule systems face growing consumer concern over plastic waste. The coffee maker B2B sourcing guide covers format selection in detail.
Online now captures 35-40% of EU kitchen appliance sales, up from approximately 25% in 2020. Social commerce, brand-owned DTC websites, and marketplace platforms are all contributing to channel growth. Products designed for physical retail — minimal online content, no digital asset package, packaging not optimised for parcel delivery — are losing shelf space to online-ready competitors.
Germany (20.8%), UK (16.6%), and France (~16%) together account for over half of European small kitchen appliance revenue. Germany remains the dominant market with a preference for premium engineering and energy efficiency. The UK shows the highest forecast growth rate. France leads on repairability legislation with its mandatory repairability index. Any Q4 sourcing plan that treats Europe as a single market is leaving margin on the table in at least one of these three countries.
Signal 1: The Air Fryer Format Shift
Air fryers are still growing. But what is growing is not what most importers are ordering.
The entry-level single basket digital air fryer — 3.5L to 5L, digital display, four presets, CE only — is now a discounter product. Lidl, Aldi, and Carrefour private labels occupy the sub-€50 shelf. An importer placing a Q4 order dominated by this format is competing on price against retailers who own the shelf.
The growth has moved to three formats:
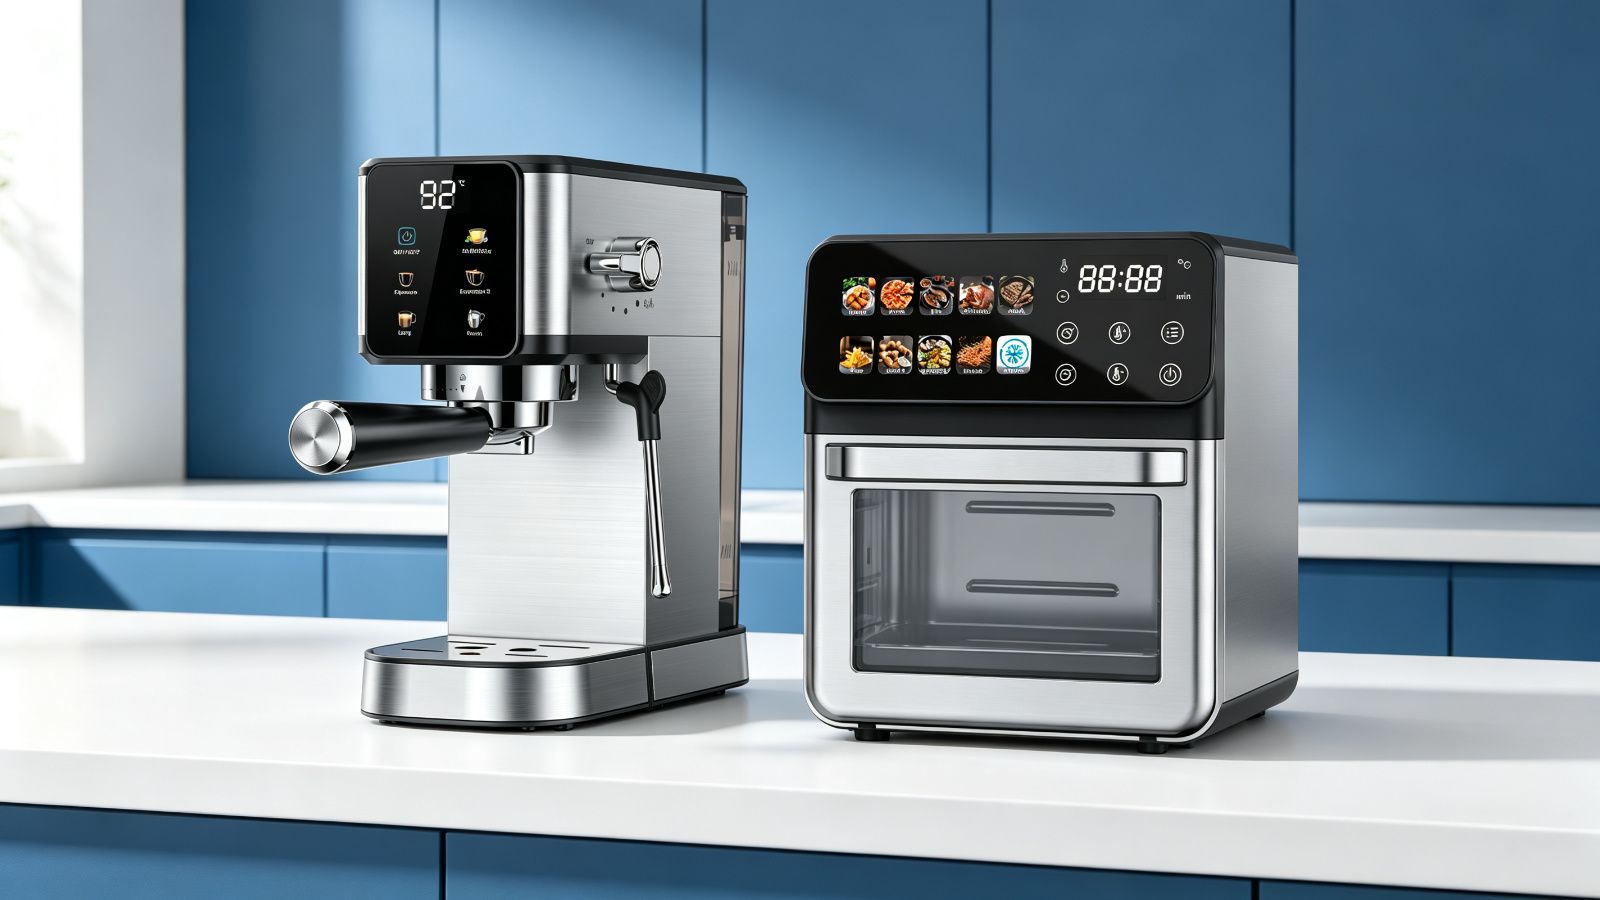
Dual basket air fryers (6L–11L total). The fastest-growing sub-segment within air fryers. Retail price band €89–€149. Justifies premium shelf placement in DACH and Benelux specialty retail. For a detailed format comparison, the dual basket vs single basket guide covers margin, certification, and channel fit.
XL capacity air fryers (6L+ single basket) and air fryer ovens (10L–25L). Competing with countertop convection ovens rather than other air fryers. Strong in Eastern Europe as a family value proposition. The large capacity air fryer oven sourcing guide covers the format's distinct shipping and certification considerations.
Multi-function air fryers with grill, steam, and rotisserie capability. The premium end of the format spectrum. Lower volume, higher per-unit margin, best suited to DACH and Nordic specialty retail with full certification packages.
What this means for your Q4 order. If your air fryer line plan for Q4 is more than 50% single basket digital units, rebalance toward dual basket and XL formats before placing the PO. The air fryer market saturation analysis provides broader category context.
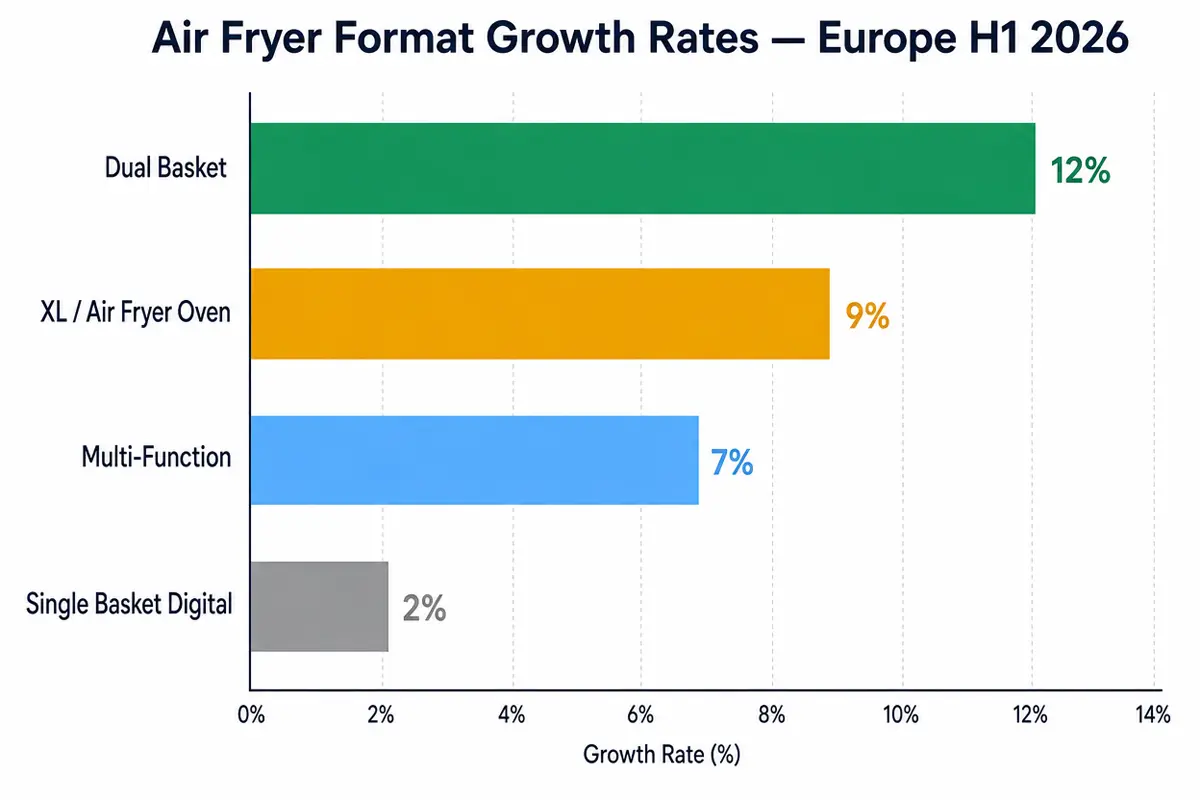
Single basket digital air fryer growth is flattening. Dual basket, XL capacity, and multi-function formats are driving the category's 6.8% CAGR. A Q4 order dominated by entry-level single basket units is a bet against the format shift.
Signal 2: Coffee Machine Premiumisation
Coffee machines generated 16.4% of all European small kitchen appliance revenue in H1 2026 — more than any other single category. The value is not in selling more units. It is in selling more expensive units.
Three sub-trends are reshaping the category:
Bean-to-cup is taking share from pods. Fully automatic espresso machines — grind beans, brew, froth milk, self-clean — are the fastest-growing coffee sub-segment. Retail prices span €300 to €1,200+, carrying importer margins that entry-level filter and pod machines cannot match. The fully automatic coffee machine sourcing guide covers OEM specifications, certification requirements, and target markets for this format.
Pod systems face a sustainability problem. Nestlé's Dolce Gusto and Nespresso-compatible systems still sell volume, but consumer and regulatory pressure on single-use plastic pods is intensifying — particularly in France and Germany. Importers heavily weighted toward pod-compatible machines should model a scenario where pod-system growth flattens or declines in Western European markets over the next 2–3 years.
Smart connectivity is becoming a premium baseline. App-based recipe guidance, automatic maintenance alerts, and voice-assistant integration are no longer novelty features — they are expected at the €400+ price point. Philips launched the app-connected Series 5000 fully automatic espresso machine in 2024, competing directly with JURA and De'Longhi at the premium tier.
What this means for your Q4 order. If your coffee machine line consists entirely of entry-level filter and pod machines, add one bean-to-cup SKU — even at low volume — to test channel acceptance before the 2027 product cycle. The German market sourcing guide and private label launch guide cover the certification and brand positioning requirements for premium coffee machine imports.
Signal 3: The Online Channel Shift
Online sales now account for 35–40% of EU kitchen appliance purchases, growing at over 5.6% annually (Grand View Research, 2026). This is not a COVID hangover. It is a structural shift, and it changes three things for B2B importers.
Packaging must survive parcel delivery, not pallet delivery. A product packaged for retail shelf display — thin cardboard, minimal internal bracing, attractive but fragile outer box — fails in e-commerce. Parcel carriers drop, stack, and tumble packages. Online-ready packaging requires drop-tested outer cartons and internal bracing that keeps the product intact through single-unit delivery. Ask your supplier for ISTA 3A or equivalent drop-test certification before specifying e-commerce packaging.
Product content is now a sourcing requirement, not a marketing afterthought. An Amazon listing or a retailer's product detail page needs high-resolution images, feature videos, comparison tables, and specification sheets. Suppliers who provide a complete digital asset package — lifestyle photography, 360-degree product views, spec sheets in editable formats — reduce the importer's post-production content cost by weeks and thousands of euros. Ask for the digital asset package at RFQ stage, not after the first shipment.
Channel conflict between physical retail and online pricing is real. A product listed at €79 on a retailer's shelf and €64 on Amazon creates channel conflict that retailers resolve by dropping the SKU. If your Q4 order serves both physical retail and online channels, differentiate the SKUs — different model numbers, different bundled accessories, or different colourways — to prevent direct price comparison from destroying one channel's margin.
What this means for your Q4 order. Add one online-ready SKU per product category: drop-tested packaging, complete digital asset package, and a model number distinct from your physical retail SKU. The kitchen appliance logistics guide covers packaging and shipping considerations for e-commerce fulfilment.
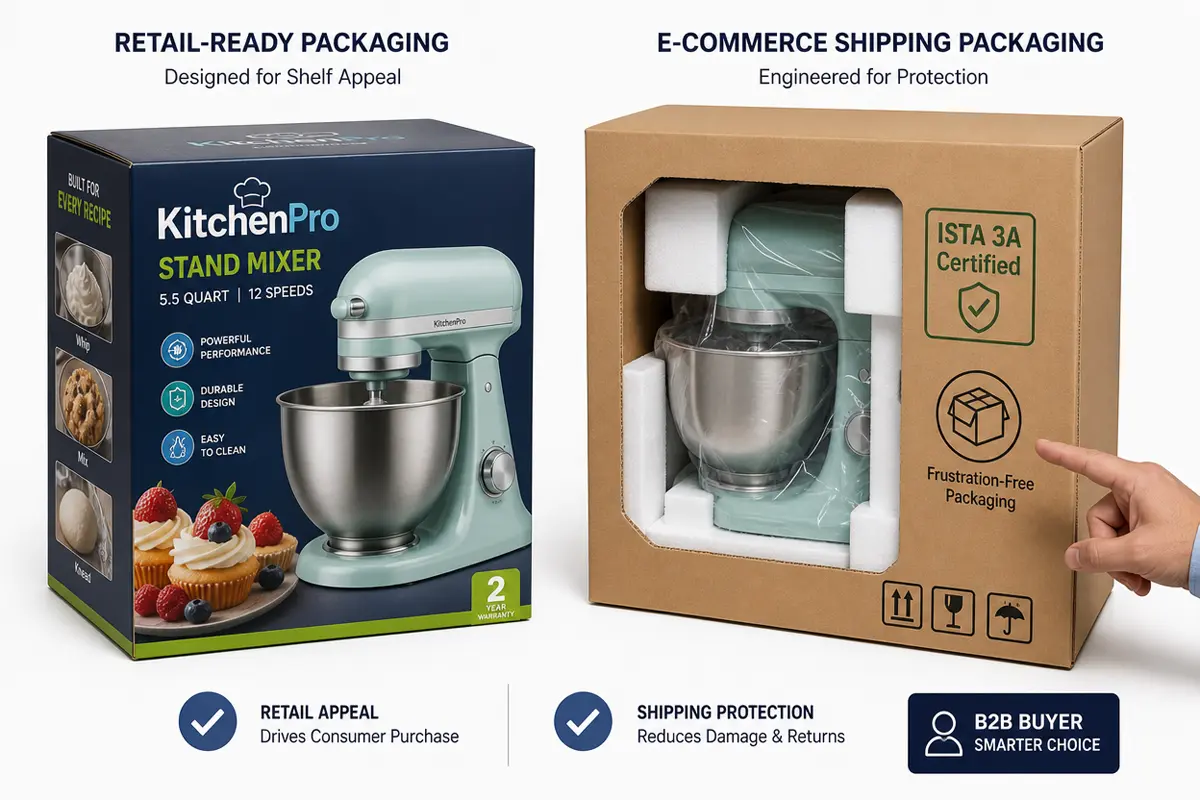
Physical retail packaging (left) prioritises shelf presence. E-commerce packaging (right) prioritises parcel survival. A Q4 order that does not include at least one online-ready SKU with drop-tested packaging is a Q4 order that cannot reach 35-40% of the market.
Your Q4 Order Checklist
: Three Adjustments Before the PO Goes Out
Explore APEXDURA's multi-category kitchen appliance range → Dual basket air fryers, fully automatic coffee machines, and e-commerce-ready packaging options available — with digital asset packages confirmed at RFQ stage. https://www.apexdura.com/products/
📊 From APEXDURA's Export Desk
In buyer conversations during the first half of 2026, the importers who adjusted their Q3 and Q4 orders based on category-level data — shifting air fryer volume toward dual basket, adding a premium coffee SKU, and specifying e-commerce packaging for at least one SKU per category — placed their POs by mid-July and secured production slots before the factory backlog built. The importers who treated Q4 as a repeat of Q3 are placing the same orders, for the same formats, through the same channels — and competing on price against retailers who own the shelf and the data.
Frequently Asked Questions
Is the air fryer market still worth entering in H2 2026?
Yes, but not with a single basket digital model at €49 retail. Enter with a dual basket or XL format at €89–€139, targeted to DACH or Benelux specialty retail, with GS and LFGB documentation. Entry-level single basket is a volume-and-price game that new entrants lose to established private-label relationships.
Should I add a bean-to-cup coffee machine to my line if my current range is all entry-level?
Yes — at low volume, as a market test. One 20ft container with a single bean-to-cup SKU placed with a DACH or French retail buyer generates more useful channel feedback than six months of market research. If it sells through, scale in 2027. If it does not, you have learned which specification, price point, or feature set your channel requires — without overcommitting inventory.
What is the minimum investment to make a SKU e-commerce-ready?
Drop-tested packaging adds approximately 0.80 per unit at the factory level, depending on carton specification and internal bracing material. A basic digital asset package — 5–10 high-resolution images, one feature video, and a formatted specification sheet — adds minimal per-unit cost when ordered at production quantity. The real cost of not having these assets is a product page that cannot convert online traffic, in a channel that now represents 35–40% of sales.
How do I prevent channel conflict between my online and retail pricing?
Differentiate the SKUs. Use distinct model numbers for online versus retail channels. Bundle online SKUs with an accessory (extra filter, cleaning kit, recipe book) that the retail SKU does not include, creating a value difference that justifies any price difference. The private label launch guide covers SKU differentiation strategies for multi-channel importers.
When should I place my Q4 order to capture these three signals?
July. Production slot booking, sea freight booking, and peak season surcharge avoidance all converge on a July decision window. An order placed in July arrives in October — in time for Q4 shelf placement. An order placed in September arrives in December — in time for clearance pricing. The Q3 production slot planning guide breaks down the week-by-week timeline.
Adjust your Q4 order based on H1 2026 market data.
Send us your current Q4 order plan — we'll confirm APEXDURA dual basket air fryer availability, bean-to-cup coffee machine specifications, and e-commerce-ready packaging options within 24 hours.
Request Q4 Sourcing Consultation →
Source Data-Driven Kitchen Appliances with APEXDURA
APEXDURA is the international brand of Zhongshan Zhenmei Electrical Appliance Co., Ltd. — 16 years of OEM/ODM manufacturing experience, 500,000 units annual output, and 0.8% defect rate across 12 production lines.
Multi-category, multi-format, multi-channel sourcing — confirmed at RFQ stage:
- ✅ Dual basket and XL capacity air fryers with GS, LFGB, and CE documentation — production slots available for Q4 delivery
- ✅ Fully automatic bean-to-cup coffee machines with smart connectivity — specifications and certifications confirmed per target market
- ✅ E-commerce-ready packaging with ISTA 3A drop-test certification and complete digital asset packages — available for all product categories
- ✅ SKU differentiation support: distinct model numbers, accessory bundles, and packaging variants for multi-channel importers
Every enquiry receives a response within 24 hours, with product availability, certification status, and production slot confirmed.
📧 Email: devin@zszhenmei.com 📱 WhatsApp: +86 136 1272 5240 🔗 Request a Sourcing Quote →