


Netherlands and Belgium: Gateway Markets for Kitchen Appliance B2B Distribution in Europe

Rotterdam handles over 14 million TEUs annually — for kitchen appliance importers shipping from China, it is not just a port, it is a distribution decision.
You have Germany covered. France is in the plan. But your container arrives in Rotterdam regardless.
Most kitchen appliance importers treating the Netherlands as a transit stop are leaving a market behind. The Benelux region — Netherlands, Belgium, and Luxembourg combined — represents one of Europe's highest per-capita consumer spending markets for household appliances, with distribution infrastructure that reaches Germany, France, and Scandinavia within 24 hours by road.
This guide covers what B2B buyers and importers need to know before treating Benelux as either their primary market or their European logistics anchor.
Key Facts
-
The Netherlands kitchen appliances market reached USD 2.94 billion in 2025, projected to grow to USD 4.60 billion by 2034 — a CAGR of approximately 5.1%, driven by smart appliance adoption and premium product demand. (Source: IMARC Group, Netherlands Kitchen Appliances Market Report, 2026)
-
In 2026, the Netherlands smart kitchen appliance segment alone is projected to surpass EUR 890 million, within a total kitchen appliance market exceeding EUR 3.0 billion — making smart and connected appliances the fastest-growing subsegment. (Source: SourceReady, Netherlands Smart Kitchen Appliances Market Report, June 2026)
-
The Port of Rotterdam is Europe's largest container port, handling the majority of container shipments arriving from China — in 2024, imports from China into the Netherlands reached USD 53.17 billion, representing 8.6% of total Dutch imports. (Source: Belgium-China Chamber of Commerce, February 2026)
-
The Netherlands household goods wholesaling industry has a market size of EUR 144.4 billion in 2026, growing at 4.7% annually — a wholesale infrastructure that Chinese OEM suppliers can access directly through Dutch and Belgian distributors without requiring a local subsidiary. (Source: IBISWorld, Netherlands Household Goods Wholesaling, 2026)
-
The Dutch government's energy label regulations require manufacturers and suppliers to create and display energy labels for applicable electrical appliances — a compliance step that must be confirmed per product category before goods enter the market. (Source: Business.gov.nl, Energy Labelling in the Netherlands)
Why the Netherlands Is More Than a Transit Hub
Rotterdam is not a starting point for your distribution. It is a strategic decision.
Importers who route containers through Rotterdam and immediately redirect stock to Germany or France are often overlooking the Netherlands itself — a market of 18 million consumers with among the highest household appliance spending rates in Europe.
Dutch retail channels are well-developed and accessible to B2B importers:
- Online retail (Bol.com is the dominant marketplace, comparable to Amazon.co.uk in UK market share terms)
- Consumer electronics chains (MediaMarkt, Coolblue — both carry extensive kitchen appliance ranges)
- Specialty kitchen and lifestyle retail (HEMA, Blokker, and premium independent kitchenware chains)
- Foodservice and HoReCa wholesale — hotel and restaurant restocking, a consistent B2B volume channel
For kitchen appliance importers, the practical advantage of the Netherlands is consolidated distribution. A single warehouse in the Rotterdam or Amsterdam logistics corridor can serve Netherlands retail, ship cross-border to Belgium within hours, and reach German distribution centres by overnight truck. This is the Benelux logistics proposition — and it is the reason why many European brand owners locate their primary EU inventory in the Netherlands even when their end market is elsewhere.
Buyers interested in the broader European distribution logistics picture can review the China-Europe kitchen appliance logistics guide for freight routing, transit times, and cost structure from Chinese OEM factories.
📊 From APEXDURA's Export Desk
Among our European clients, those who designate the Netherlands as their primary EU receiving port consistently report shorter total supply chain cycles compared to those routing through Southern European ports. The combination of Rotterdam's handling efficiency, the density of Dutch third-party logistics providers with kitchen appliance experience, and the proximity to major German retail distribution centres makes the Netherlands a logistics decision that pays for itself in reduced transit time — independent of whether it is the end market.
Benelux Distribution Reach: One Container, Five Markets

A container arriving at Rotterdam or Antwerp can reach Germany, France, the UK, and Scandinavia by truck within 24–48 hours — making Benelux the most capital-efficient European distribution anchor for most kitchen appliance importers.
The geographic logic of Benelux as a distribution hub is straightforward:
Antwerp, Belgium's port, adds a second entry point 80 km from Rotterdam — with comparable container handling capacity and established connections to French and Southern European logistics routes. For importers serving both Northern and Southern Europe, splitting container arrivals between Rotterdam and Antwerp is a common optimisation.
The Poland and Eastern Europe sourcing guide covers the Eastern extension of this hub-and-spoke logic — Polish distribution centres are increasingly used as secondary hubs for Central and Eastern European fulfilment after initial arrival in Rotterdam.
Explore APEXDURA's full kitchen appliance range for Benelux and Northern European distribution → CE-compliant product designs ready for Dutch and Belgian market entry. Request specifications and MOQ details. View full product range
Belgium: The EU Administrative Market
Belgium is frequently underestimated by importers who focus exclusively on the Netherlands. But Belgium has a distinct B2B character worth understanding:
Brussels is the de facto capital of EU institutions — the European Commission, Council, and Parliament are all headquartered there. This creates a concentrated cluster of large-scale procurement operations: EU institutional purchasing, international NGOs, and multinational headquarters with regional procurement teams that buy kitchen appliances at volume for office facilities, canteens, and hospitality functions.
Belgian retail channels differ from Dutch channels in language and distribution:
- Dutch-speaking Flanders (north) — consumer preferences and retail chains largely mirror the Netherlands
- French-speaking Wallonia (south) — aligns more closely with French consumer expectations, including attention to sustainability and repairability
For kitchen appliance importers, this means Belgium effectively requires bilingual product documentation — Dutch and French language manuals and packaging for full market coverage. Sourcing from a factory that supports multi-language documentation from the outset reduces this friction significantly. APEXDURA's OEM customisation capabilities include instruction manuals in 12 European languages, covering both Dutch and French as standard.
The compliance baseline for both Netherlands and Belgium is EU standard:
- CE marking (mandatory for all electrical kitchen appliances placed on the EU market)
- RoHS compliance — see the RoHS, REACH and WEEE guide for the substance restriction framework
- LFGB testing where food-contact surfaces are present (particularly relevant for blenders and coffee machines sold into the Dutch premium retail channel)
- ErP standby power requirements where applicable — see the ErP 2026 guide
There is no GS mark requirement in the Netherlands or Belgium (that is specific to the German market — see the GS certification guide). This makes Benelux a slightly lower-compliance-overhead entry point than Germany for importers testing a new product category.
What Dutch and Belgian Buyers Actually Want

Dutch retail environments set a high visual and quality bar — importers supplying the Netherlands should expect product presentation requirements that go beyond CE compliance.
Dutch and Belgian B2B buyers have several consistent sourcing priorities that distinguish them from buyers in Germany or Eastern Europe:
Sustainability credentials matter earlier in the buying conversation. Dutch buyers — particularly those supplying retail chains — increasingly request product carbon footprint data and packaging recyclability information at the RFQ stage, not just at final compliance review. The trajectory toward ESPR Digital Product Passport requirements is actively discussed in Dutch procurement circles.
Energy efficiency is a genuine differentiator, not just a compliance box. The Netherlands has consistently led EU member states in consumer awareness of energy labelling. Products with strong ErP performance (particularly low standby consumption) are positioned as premium in Dutch retail, not just as legally compliant.
Premium positioning is the growth segment. The EUR 890 million smart appliance sub-market is not driven by price competition — Dutch consumers are willing to pay a premium for connected, multi-function, and aesthetically designed appliances. Importers sourcing for this segment should evaluate smart multi-cookers and premium coffee machines as priority SKUs. The blender B2B guide covers the high-speed commercial blender segment that performs particularly well in Dutch foodservice channels.
When Benelux is not the right first market: If your product is in the entry-level price tier (under EUR 30 retail) and you have not yet established a European wholesale relationship, the Netherlands is a competitive market to start in — Dutch consumers have strong brand familiarity and price comparison capability. Eastern European markets may offer faster initial traction for basic-tier products. See the Poland and Eastern Europe guide and the European mid-year market check for where volume opportunities exist at different price points.
Your 90-Day Action Plan for Benelux Market Entry
This week: Pull your last 12 months of shipment records. If Rotterdam is already your arrival port, calculate what percentage of that container volume was allocated to Netherlands local distribution versus immediate transhipment. That gap is your Benelux opportunity size.
FAQ
Q1: Is the Netherlands a large enough market to justify dedicated distribution investment? Yes, for mid-to-premium product tiers. At USD 2.94 billion in 2025 and growing at ~5% annually, the Netherlands kitchen appliance market is comparable in size to markets like Poland that importers routinely prioritise. The difference is price positioning — the Netherlands rewards premium specification, while Poland rewards volume pricing. For a full picture of where price-sensitive volume sits, see the Poland and Eastern Europe guide.
Q2: Do I need a local Dutch or Belgian entity to sell into the Benelux market? Not necessarily. Many importers operate through a local distribution partner or EU-registered authorised representative. What you do need is CE documentation naming an EU-based importer or authorised representative — this can be a third-party service, not necessarily your own legal entity. Confirm your CE Declaration of Conformity structure before the first container ships.
Q3: What certifications do I need beyond CE for the Netherlands and Belgium? CE and RoHS are the mandatory baseline. LFGB testing is recommended for food-contact appliances (blenders, coffee machines) if targeting premium retail channels — some Dutch retailers request it even though it is technically a German national requirement. GS certification is not required for the Netherlands or Belgium. For detailed certification planning, see the CE certification guide and GS certification guide.
Q4: How does Belgium's language split affect product documentation? Products sold across Belgium need documentation in both Dutch and French. Packaging, instruction manuals, safety warnings, and warranty cards should all be available in both languages. Importers sourcing from OEM manufacturers with multi-language documentation support can include both versions in a single print run, avoiding separate SKU management.
Q5: Is it more cost-effective to use Rotterdam or Antwerp as the entry port? Both are viable. Rotterdam typically has shorter handling times for containers arriving directly from Chinese ports. Antwerp offers competitive pricing and is better positioned for onward distribution to France and Southern Europe. For most kitchen appliance importers primarily targeting the Northern European market, Rotterdam is the default — but confirming with your freight forwarder based on current port congestion and handling fees is recommended. The China-Europe logistics guide covers the freight cost comparison in detail.
Ready to plan your Benelux distribution with CE-compliant kitchen appliances from APEXDURA? Send us your target product category, volume estimate, and market. We will confirm which SKUs are CE and LFGB documented, and provide MOQ and lead time within 24 hours. Submit your sourcing enquiry →
Source Kitchen Appliances for Benelux Distribution with APEXDURA
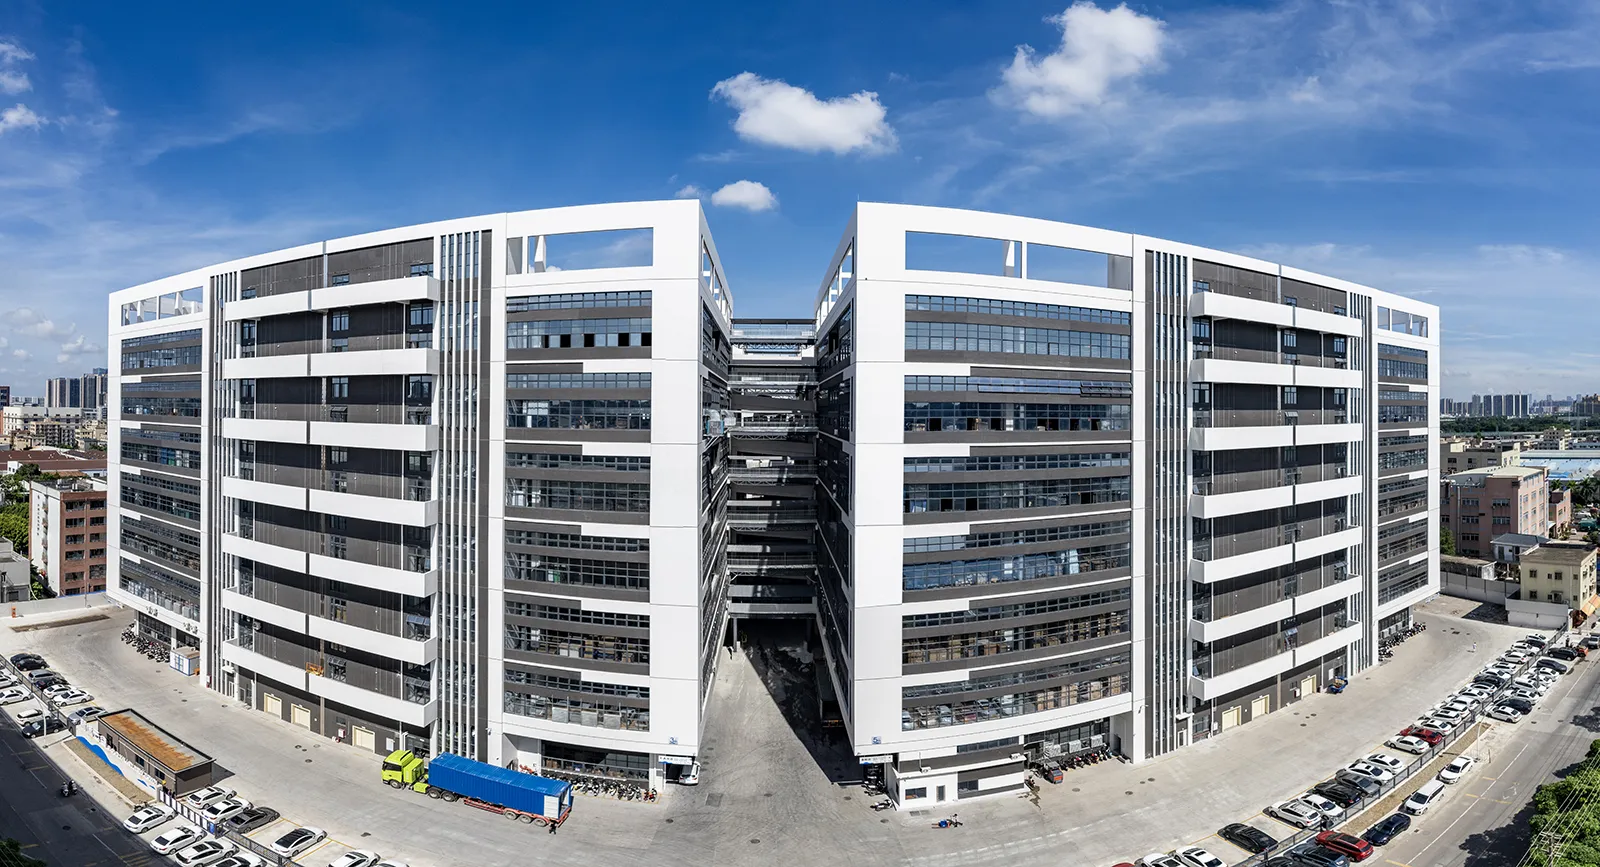
16 years of OEM/ODM manufacturing. 500,000 units annual output. 0.8% defect rate.
✅ CE + RoHS + LFGB documentation available — suitable for Dutch premium retail and Belgian bilingual market requirements, with importer name on declaration ✅ Dutch and French multilingual manuals — as standard for European OEM orders; no separate SKU management required ✅ Full product range covering air fryers, coffee machines, blenders, electric pressure cookers, microwave ovens — single factory, consolidated shipment from one source ✅ Flexible MOQ — supports initial Benelux market test before committing to full distribution volume
Every enquiry receives a response within 24 hours, with product availability, MOQ, and lead time confirmed.
📧 Email: devin@zszhenmei.com 📱 WhatsApp: +86 136 1272 5240 🔗 Request a Sourcing Quote →