


Scandinavia Kitchen Appliance Market: Sourcing Guide for Brands and Importers (2026)
The Nordic market is small by volume but disproportionately important for premium kitchen appliance brands. Higher disposable income, strong design consciousness and early adoption of sustainability standards make Sweden, Norway, Denmark and Finland attractive target markets for private label programs.
But the region is not a single market. Each country has different retail structures, regulatory nuances and consumer expectations. Brands that treat Scandinavia as one uniform market often underperform.
This guide breaks down the Scandinavian kitchen appliance landscape by country, channel and product category — and what it means for your sourcing strategy.
- Scandinavian consumers prioritize design, durability and sustainability over lowest price — premium positioning works better than discount positioning
- Each Nordic country has a distinct retail structure; a single distributor rarely covers all four markets effectively
- Sustainability claims require substance. Recycled materials, repairability and energy efficiency are expected, not just marketing talking points
- Certification requirements are broadly aligned with EU standards (CE), but Norway and Denmark have stronger market surveillance and local certification traditions
Key Facts
- Combined population of the four main Nordic markets is approximately 27 million, with among the highest per-capita household disposable income in Europe and correspondingly higher average selling prices for small kitchen appliances.
- Sweden is the largest individual market by volume, followed by Denmark, Norway and Finland, but Norway shows the highest average unit price due to stronger premium segment demand and higher overall consumer spending power.
- Sustainability and circular economy expectations are more advanced in Scandinavia than in most of Europe, with consumers paying attention to repairability, recycled content and product lifespan — trends that are gradually spreading to the rest of the EU.
- Specialist electrical retailers remain strong across the region, alongside growing online channels. Pure discount grocery channel penetration for small appliances is lower than in Southern or Eastern Europe.
- The EU Right to Repair directive has particular resonance in Nordic markets, where consumer organizations and environmental groups have been pushing for longer product warranties and easier repair access for several years.
Country-by-Country Market Profile
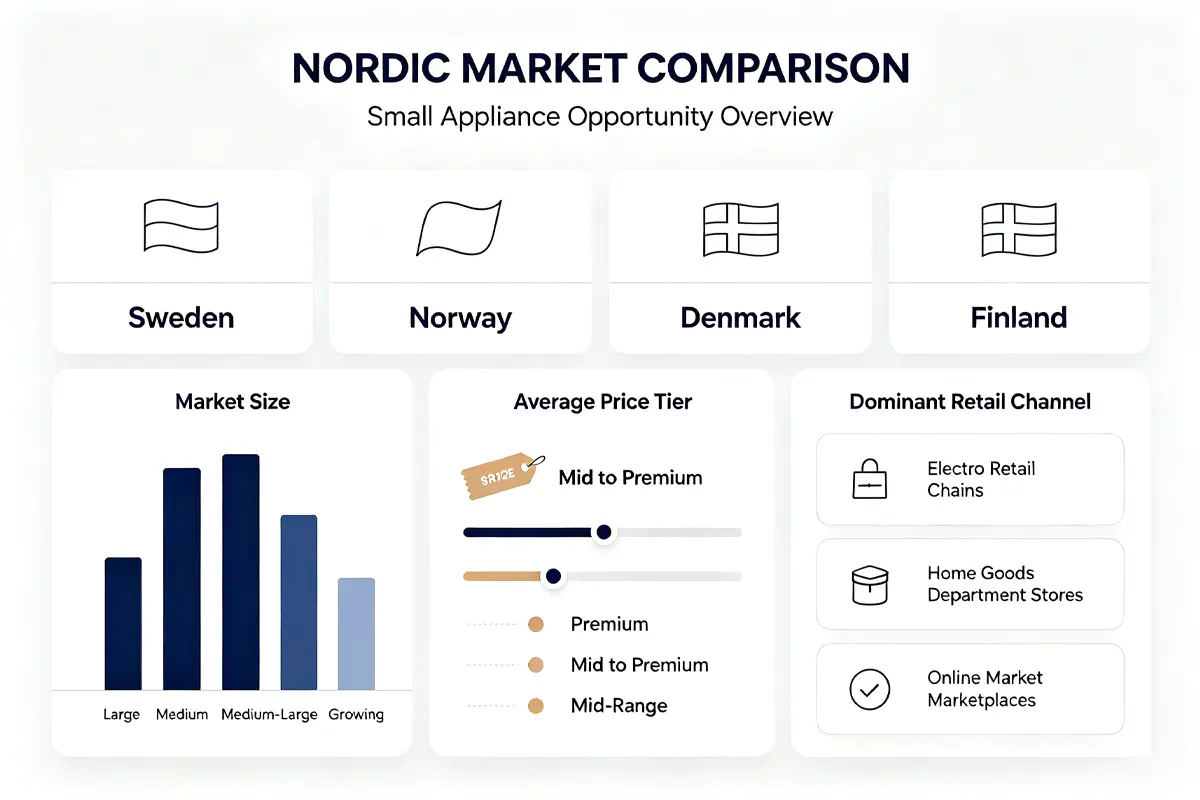
Figure 1: Scandinavian kitchen appliance market comparison by country — size, price tier and channel structure
Sweden
The largest Nordic market by population and total appliance volume. Sweden has a mature, competitive retail landscape with strong specialist chains, well-established online players and a growing discount segment. Swedish consumers are early adopters of new product categories — air fryers penetrated faster here than in many other European markets.
Sustainability is a mainstream purchasing factor rather than a niche concern. Energy efficiency class, material transparency and brand environmental positioning all influence buying decisions. For B2B buyers, Sweden is often the first Nordic market to launch in, serving as a reference for the rest of the region.
Norway
Smaller population but the highest purchasing power in the region. Norway's average selling price for small kitchen appliances sits above the rest of Scandinavia. Premium and design-led brands perform particularly well. The market is less price-driven than Sweden or Denmark.
Norway is part of the EEA and accepts CE marking, but has its own market surveillance framework and a strong tradition of local certification (NEMKO). Retail is dominated by a smaller number of powerful chains, and entry barriers for new brands can be higher than in other Nordic markets.
Denmark
A compact, concentrated market with strong retail competition and well-developed online penetration. Danish consumers are design-conscious and have historically favored minimalist, functional aesthetics — matching closely with Scandinavian design heritage.
Denmark has active market surveillance and a strong consumer protection culture. Private label is well established across price tiers, from discount to premium. For new brands, Denmark can be a faster market to enter than Norway, with shorter decision cycles at retail buyer level.
Finland
Often grouped with Scandinavia commercially but with some distinct consumer patterns. Finland has slightly lower average selling prices than Norway and Sweden, and a retail structure that leans more toward large generalist chains and strong seasonal promotional cycles.
Finnish consumers value reliability and practicality highly. Design matters but takes a more functional form than in Denmark or Sweden. Online growth has been strong, particularly in the small appliance category.
For broader European market context, our European small kitchen appliances market overview covers the full regional picture including Southern and Eastern European markets.
Consumer and Product Trends in the Nordics
Sustainability as a Baseline Expectation
In most of Europe, sustainability is still a differentiator. In Scandinavia, it is increasingly table stakes. Consumers expect energy-efficient products, consideration of material choices, and transparency about product lifespan. Brands that lead with genuine sustainability credentials — recycled plastic content, longer warranty, repairable design — capture disproportionate attention.
The EU Right to Repair directive is watched closely in the Nordics, and some brands are already positioning ahead of the formal requirements.
Minimalist and Functional Design Aesthetic
Scandinavian design heritage shapes product expectations. Clean lines, neutral colors (white, black, stainless steel, muted tones), and uncluttered control interfaces resonate more strongly than busy, feature-heavy designs. Brands with overly colorful or decorative products can struggle to find shelf space in premium retail channels.
This design preference extends to packaging. Minimal, recyclable packaging with clear information is expected at mid-to-premium price points.
Premium Air Fryers and Multi-Cookers
Air fryers have penetrated deeply across all four Nordic markets. The growth opportunity now is in the premium and large-capacity segments — dual basket models, stainless steel finishes, and digitally connected premium versions are all showing stronger growth than entry-level units.
Multi-function countertop ovens and air fryer ovens are also gaining traction, particularly in urban households where kitchen space is limited and one appliance replacing several is a strong value proposition.
Durability Over Disposability
Nordic consumers are increasingly skeptical of short-lifespan small appliances. Brands that can demonstrate build quality, longer warranty periods, and availability of spare parts build stronger loyalty. This feeds directly into sourcing decisions — choosing factories that prioritize component quality and design for durability pays off in this region.
📊 From APEXDURA's Sourcing Desk
Nordic market orders consistently specify higher-grade internal components and more rigorous reliability testing than average European orders. The price sensitivity is lower, but the quality and durability expectations are correspondingly higher — it is a different trade-off than Southern European volume markets.
Retail and Distribution Structure
Specialist Electrical Retailers
Strong specialist chains remain the backbone of small kitchen appliance sales across the Nordics. These retailers carry curated assortments, provide product advice, and tend to work with established brands and proven private label programs. Getting listed with the major specialist chains is the primary goal for most new entrants.
Online Channels
Online penetration is advanced and growing across all four countries. Both pure-play online retailers and the online arms of physical chains are significant channels. The Nordics have high digital adoption rates and well-developed logistics infrastructure, making online a viable standalone channel for direct-to-consumer or marketplace brands.
General Merchandise and Department Stores
Large generalist chains and department stores remain relevant, particularly in Finland and Sweden. These channels often run strong seasonal promotions and can move significant volume during key sales periods, but tend to be more price-driven than specialist retailers.
Discount and Grocery
Discount channel penetration for small appliances is lower in Scandinavia than in many other European markets. Grocery channel private label appliances exist but are less dominant. Premium and mid-tier positioning is generally more profitable than trying to compete at the absolute lowest price point.
For brands building a European distribution strategy, our German market guide and French market guide cover the two largest Western European markets for comparison.
Regulatory and Compliance Notes
CE Marking Is the Baseline
All four markets accept CE marking for products placed on the market. Sweden, Denmark and Finland are EU members; Norway is in the EEA and accepts CE marking under the EEA agreement. The core directives — LVD, EMC, RoHS — apply uniformly across the region.
Stronger Market Surveillance
Where the Nordics differ is enforcement. Market surveillance authorities in Norway, Denmark and Sweden are generally considered more active and rigorous than the EU average. Product safety, chemical compliance and energy labeling are all actively checked. Products that pass in less-enforced markets can run into problems in the Nordics.
Local Certification Marks (Optional but Valuable)
NEMKO (Norway), SEMKO (Sweden), DEMKO (Denmark) and FIMKO (Finland) are local certification bodies with strong historical recognition. CE marking is sufficient legally, but local marks can add credibility with retailers and consumers, particularly in the premium segment. Whether the additional certification cost is worthwhile depends on your price tier and volume.
Our CE certification guide and GS certification guide provide more detail on how local marks interact with the baseline CE framework.
Honest Recommendation: Is the Nordic Market Right for Your Brand?
Scandinavia is a good fit if:
- Your brand positioning is mid-to-premium rather than budget
- You can support higher build quality and component specifications
- Sustainability and design are genuine strengths of your product range
- You have or can secure distribution partners with local market knowledge
- You are prepared for stricter compliance and market surveillance
Think carefully before entering if:
- Your primary competitive advantage is the lowest possible price
- You need very high volume to hit your cost targets
- You cannot invest in localized packaging, manuals and market-specific certification
- You have no existing European distribution infrastructure
The Nordic region is not a high-volume first market, but it is an excellent second or third market for brands that have already established themselves in Germany, France or the UK and want to expand into higher-margin premium territories.
Nordic Sourcing Strategy Checklist
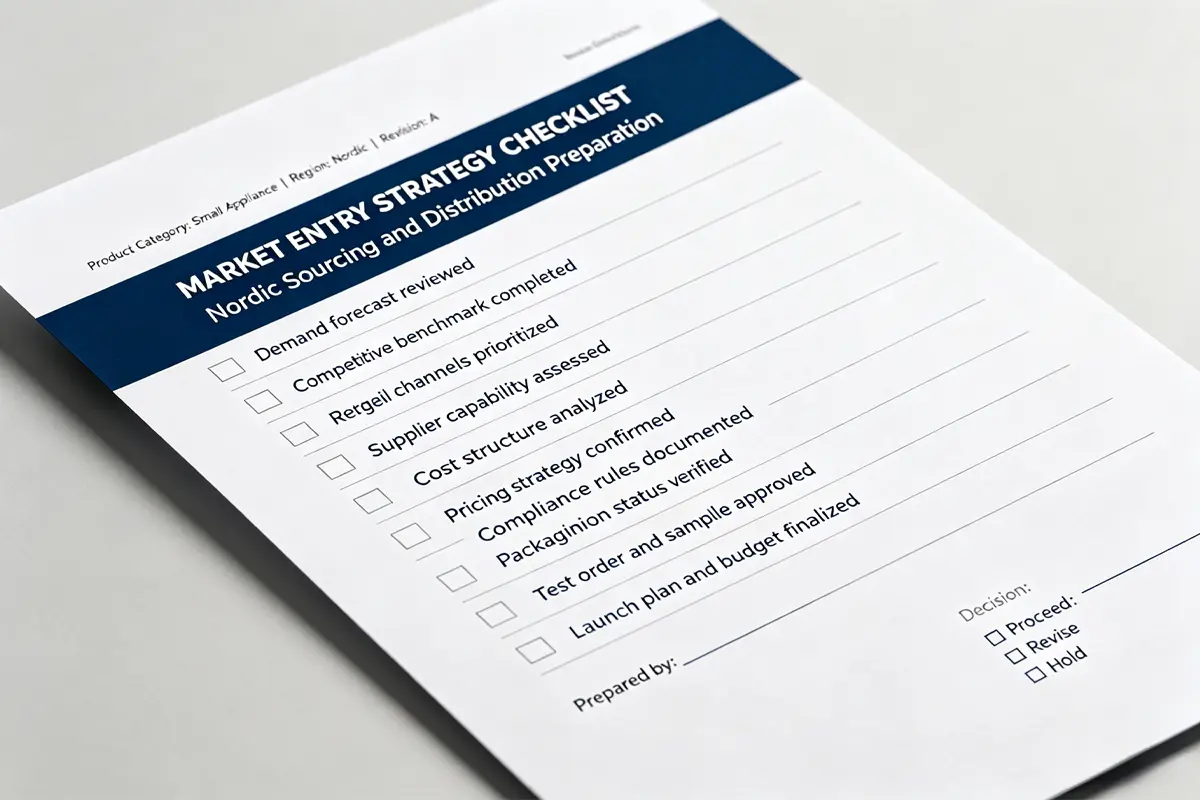
Figure 2: Nordic market entry sourcing checklist for kitchen appliance brands
FAQ
Source Premium Kitchen Appliances with APEXDURA
Planning to source kitchen appliances for the Nordic market?
Tell us your target countries and product category — we'll outline certification options, customization possibilities and typical MOQ levels for Nordic-market product specifications.
APEXDURA supplies European brands and importers with small kitchen appliances built to mid-to-premium specifications, including models suitable for Nordic market requirements.
✅ Full CE certification with current test documentation
✅ Higher-grade component options for durability-focused markets
✅ Minimalist design language and stainless steel finish options
✅ Multilingual manual and packaging support for Nordic languages
Every enquiry receives a response within 24 hours, with certification status, customization options and sample lead time confirmed upfront.
📧 Email: devin@zszhenmei.com
📱 WhatsApp: +86 136 1272 5240
🔗 Discuss Nordic Market Sourcing Requirements